


Yields Hit Highest Levels in Decades; Most Stocks Weaken, but AI Trade Returns
HIGHLIGHTS
- Stocks: The S&P 500 declined modestly in September, while the NASDAQ Composite hit a new all-time high during the month. Small caps, value, and international stocks declined, but narrow leadership reemerged from the AI trade as large-cap growth stocks advanced.
- Bonds: Yields rose dramatically in September. The 10-year U.S. Treasury closed August at 4.75%, but yields spiked higher to 5.29% during the month. The 30-year increased to 5.64% from 5.25% for the month.
- U.S. Economy: The economy continued to reflect growth and was one reason the Fed felt comfortable raising rates as it tries to curb persistent inflation. The Atlanta Fed’s GDPNow estimate for third-quarter growth stands at 3.7% (as of October 1, 2026).
- Federal Reserve: For the first time in over three years, the FOMC voted to raise the fed funds rate by 0.25%. The vote was unanimous as the Fed focuses on reining in inflation, which has stayed stubbornly above the Fed’s 2% target.
Equity Markets
Large-cap growth stocks were the one pocket of strength in September as most other areas of the market declined. Small caps struggled the most as investors worried that higher rates could impact smaller companies more acutely as these businesses tend to raise capital more frequently than larger companies; therefore, rising rates hurt – a classic Wall Street trade. See Table 1 for September, Q3, and YTD returns.
Table 1 | Equity Markets
| Index | Sept. 2026 | Q3 | YTD |
|---|---|---|---|
| S&P 500 | -0.35% | 2.30% | 12.75% |
| S&P 500 Equal Weight | -4.81% | -1.87% | 10.03% |
| DJIA | -4.12% | -2.34% | 7.19% |
| Russell 3000 | -0.84% | 1.41% | 12.42% |
| Russell 1000 Growth | 2.16% | 0.92% | 6.30% |
| Russell 1000 Value | -3.13% | 2.61% | 19.27% |
| NASDAQ Comp. | 1.93% | 2.61% | 16.09% |
| Russell 2000 | -5.25% | -7.23% | 13.71% |
| MSCI ACWI ex U.S. | -2.38% | 0.48% | 14.22% |
| MSCI Emerging Mkts Net | -0.56% | -0.37% | 23.38% |
The Russell 1000 Growth and Nasdaq Composite indices showed the best result for the month as the AI trade resumed in September. Some concerns developed about the strength of the economy and eventually earnings growth, and those companies that create their own growth (like the mega-cap technology names) advanced in this environment. Value stocks showed clear leadership in the third quarter and YTD, but growth stocks shined in September. The Russell 1000 Value Index is up 19.27% YTD and still easily outpaces the Russell 1000 Growth Index, which has gained a mere 6.30%. The script has flipped for small caps, as the Russell 2000 Index slipped more than 5% for the month and 7% for the quarter. It still has gains of better than 13.7% for the year, but small caps have struggled in recent months. International stocks have quietly reestablished some leadership after last year’s strong results with emerging markets showing their best gains so far this year. One consistent narrative supporting the stock market has been very strong earnings growth.
Expectations are still calling for earnings to grow north of 30% in 2026 and in the mid-teens in 2027, which makes the stock market cheaper from a valuation perspective today than where we began the year. While subject to revision, we are at a point in the market cycle where earnings growth has been accelerating and supporting gains in the stock market. We understand that earnings will eventually slow from these strong levels, but we have yet to see that slowdown develop. The fundamental backdrop of strong earnings continues to keep us constructive on the stock market through the balance of 2026 and into 2027, but we are mindful that higher rates could become a headwind to the stock market and bonds could provide more competition for investor dollars with rates at levels not seen in years.
Fixed Income
The rise in the 10-year U.S. Treasury has been unrelenting. The yield closed August at 4.75%, and it rose sharply to 5.29% by the end of September. The 30-year went from 5.25% to 5.64%. Rates rose sharply across the yield curve and put significant pressure on bond prices and performance struggled for the month. See Chart 1 for the rise in 10- and 30-year yields and Table 2 for September, Q3, and YTD bond index returns.
Chart 1
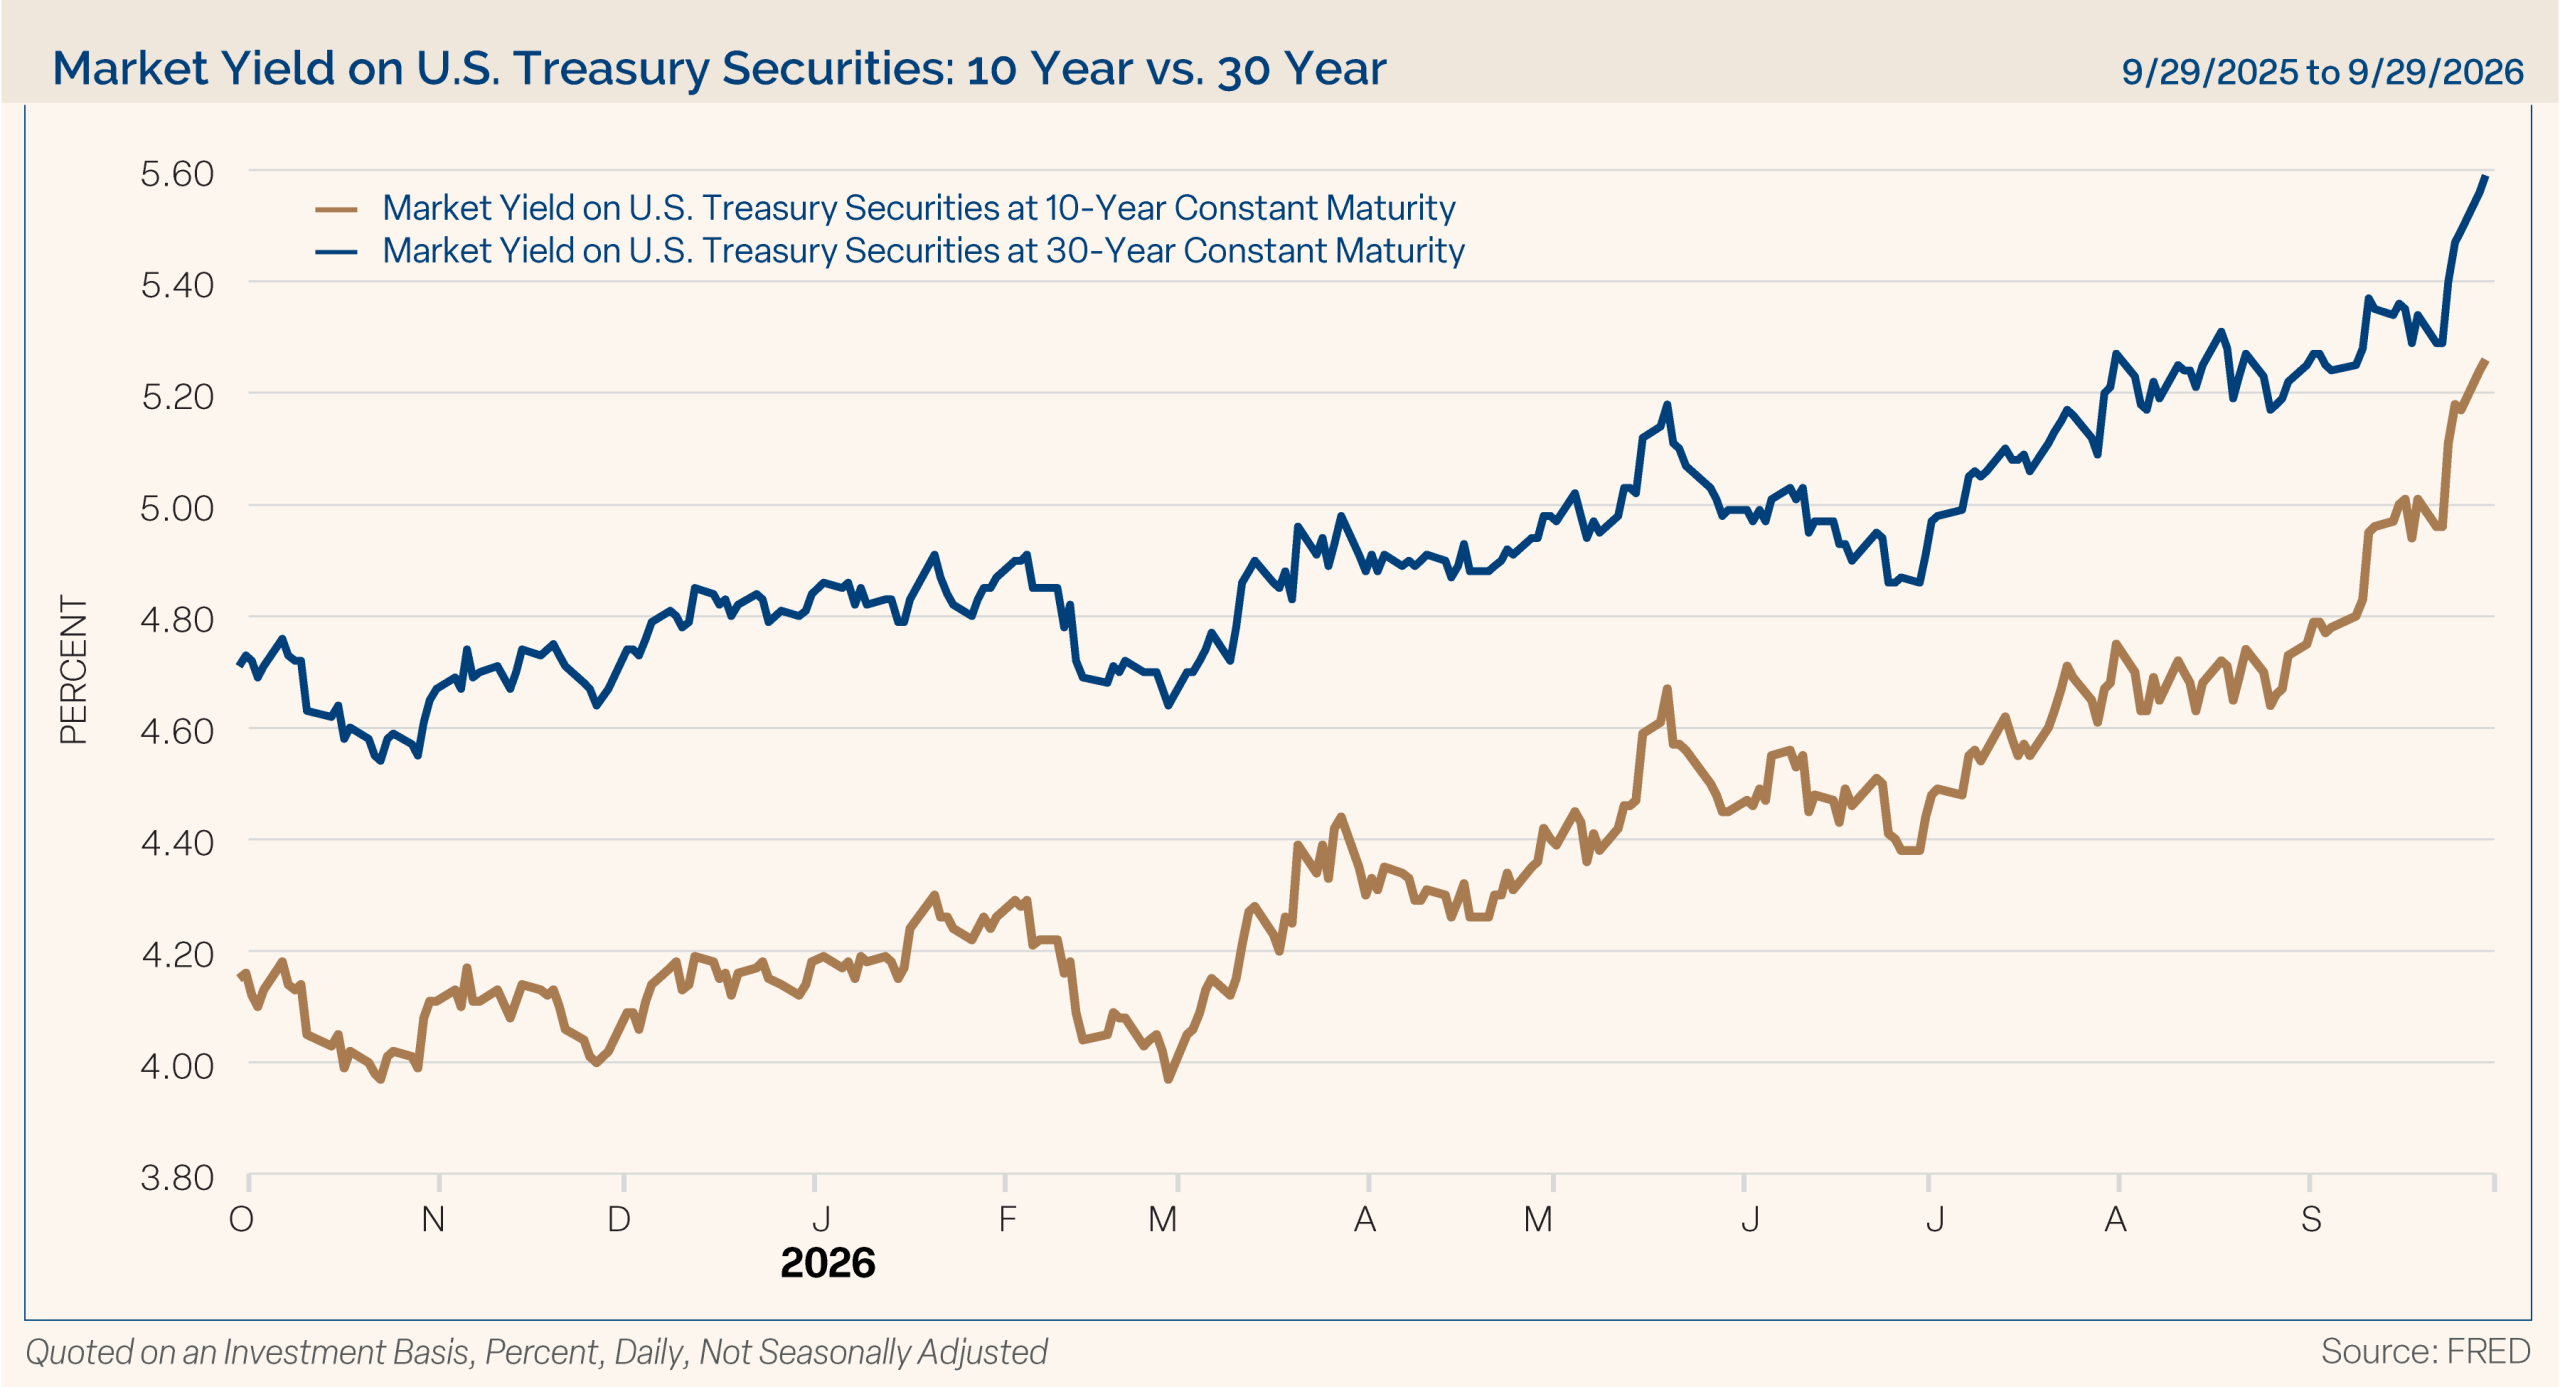
Table 2 | Fixed Income Markets
| Index | Sept. 2026 | Q3 | YTD |
|---|---|---|---|
| Bloomberg U.S. Agg | -2.61% | -3.51% | -2.91% |
| Bloomberg U.S. Credit | -2.68% | -3.83% | -3.01% |
| Bloomberg U.S. High Yld | -2.52% | -1.82% | 0.10% |
| Bloomberg Muni | -4.36% | -6.35% | -4.18% |
| Bloomberg 30-year U.S. TSY | -5.16% | -8.74% | -8.06% |
| Bloomberg U.S. TSY | -2.24% | -3.04% | -2.77% |
September and the third quarter were extremely challenging for the bond market and wiped out returns for the year with only a modest gain still evident on the high-yield side year to date. We believe it is important to remember that for clients with individual bond portfolios, we own the individual bonds for our clients. Certainly, we care what bond prices do, but we do not need to sell those bonds in environments like this. We can just hold those bonds, collect the coupon payments, and receive par value when the bond matures, assuming the bond does not default. As an active manager, we might sell bonds (and take a potential loss) to invest in higher-yielding bonds as rates rise, which could benefit clients over the longer term as higher yields could be collected in the years ahead.
We maintain our longstanding position favoring credit versus pure rate exposure, which is especially important in today’s rising rate environment. We believe the role bonds play in a portfolio, to provide stable cash flow and to help offset the volatility of stocks in the long run, has not changed. With uncertainty ahead, we believe having an active bond management approach makes sense. Rates have not been this high in decades, which, we believe, provides attractive opportunities for bond investors.
Economic Data Highlights and Outlook
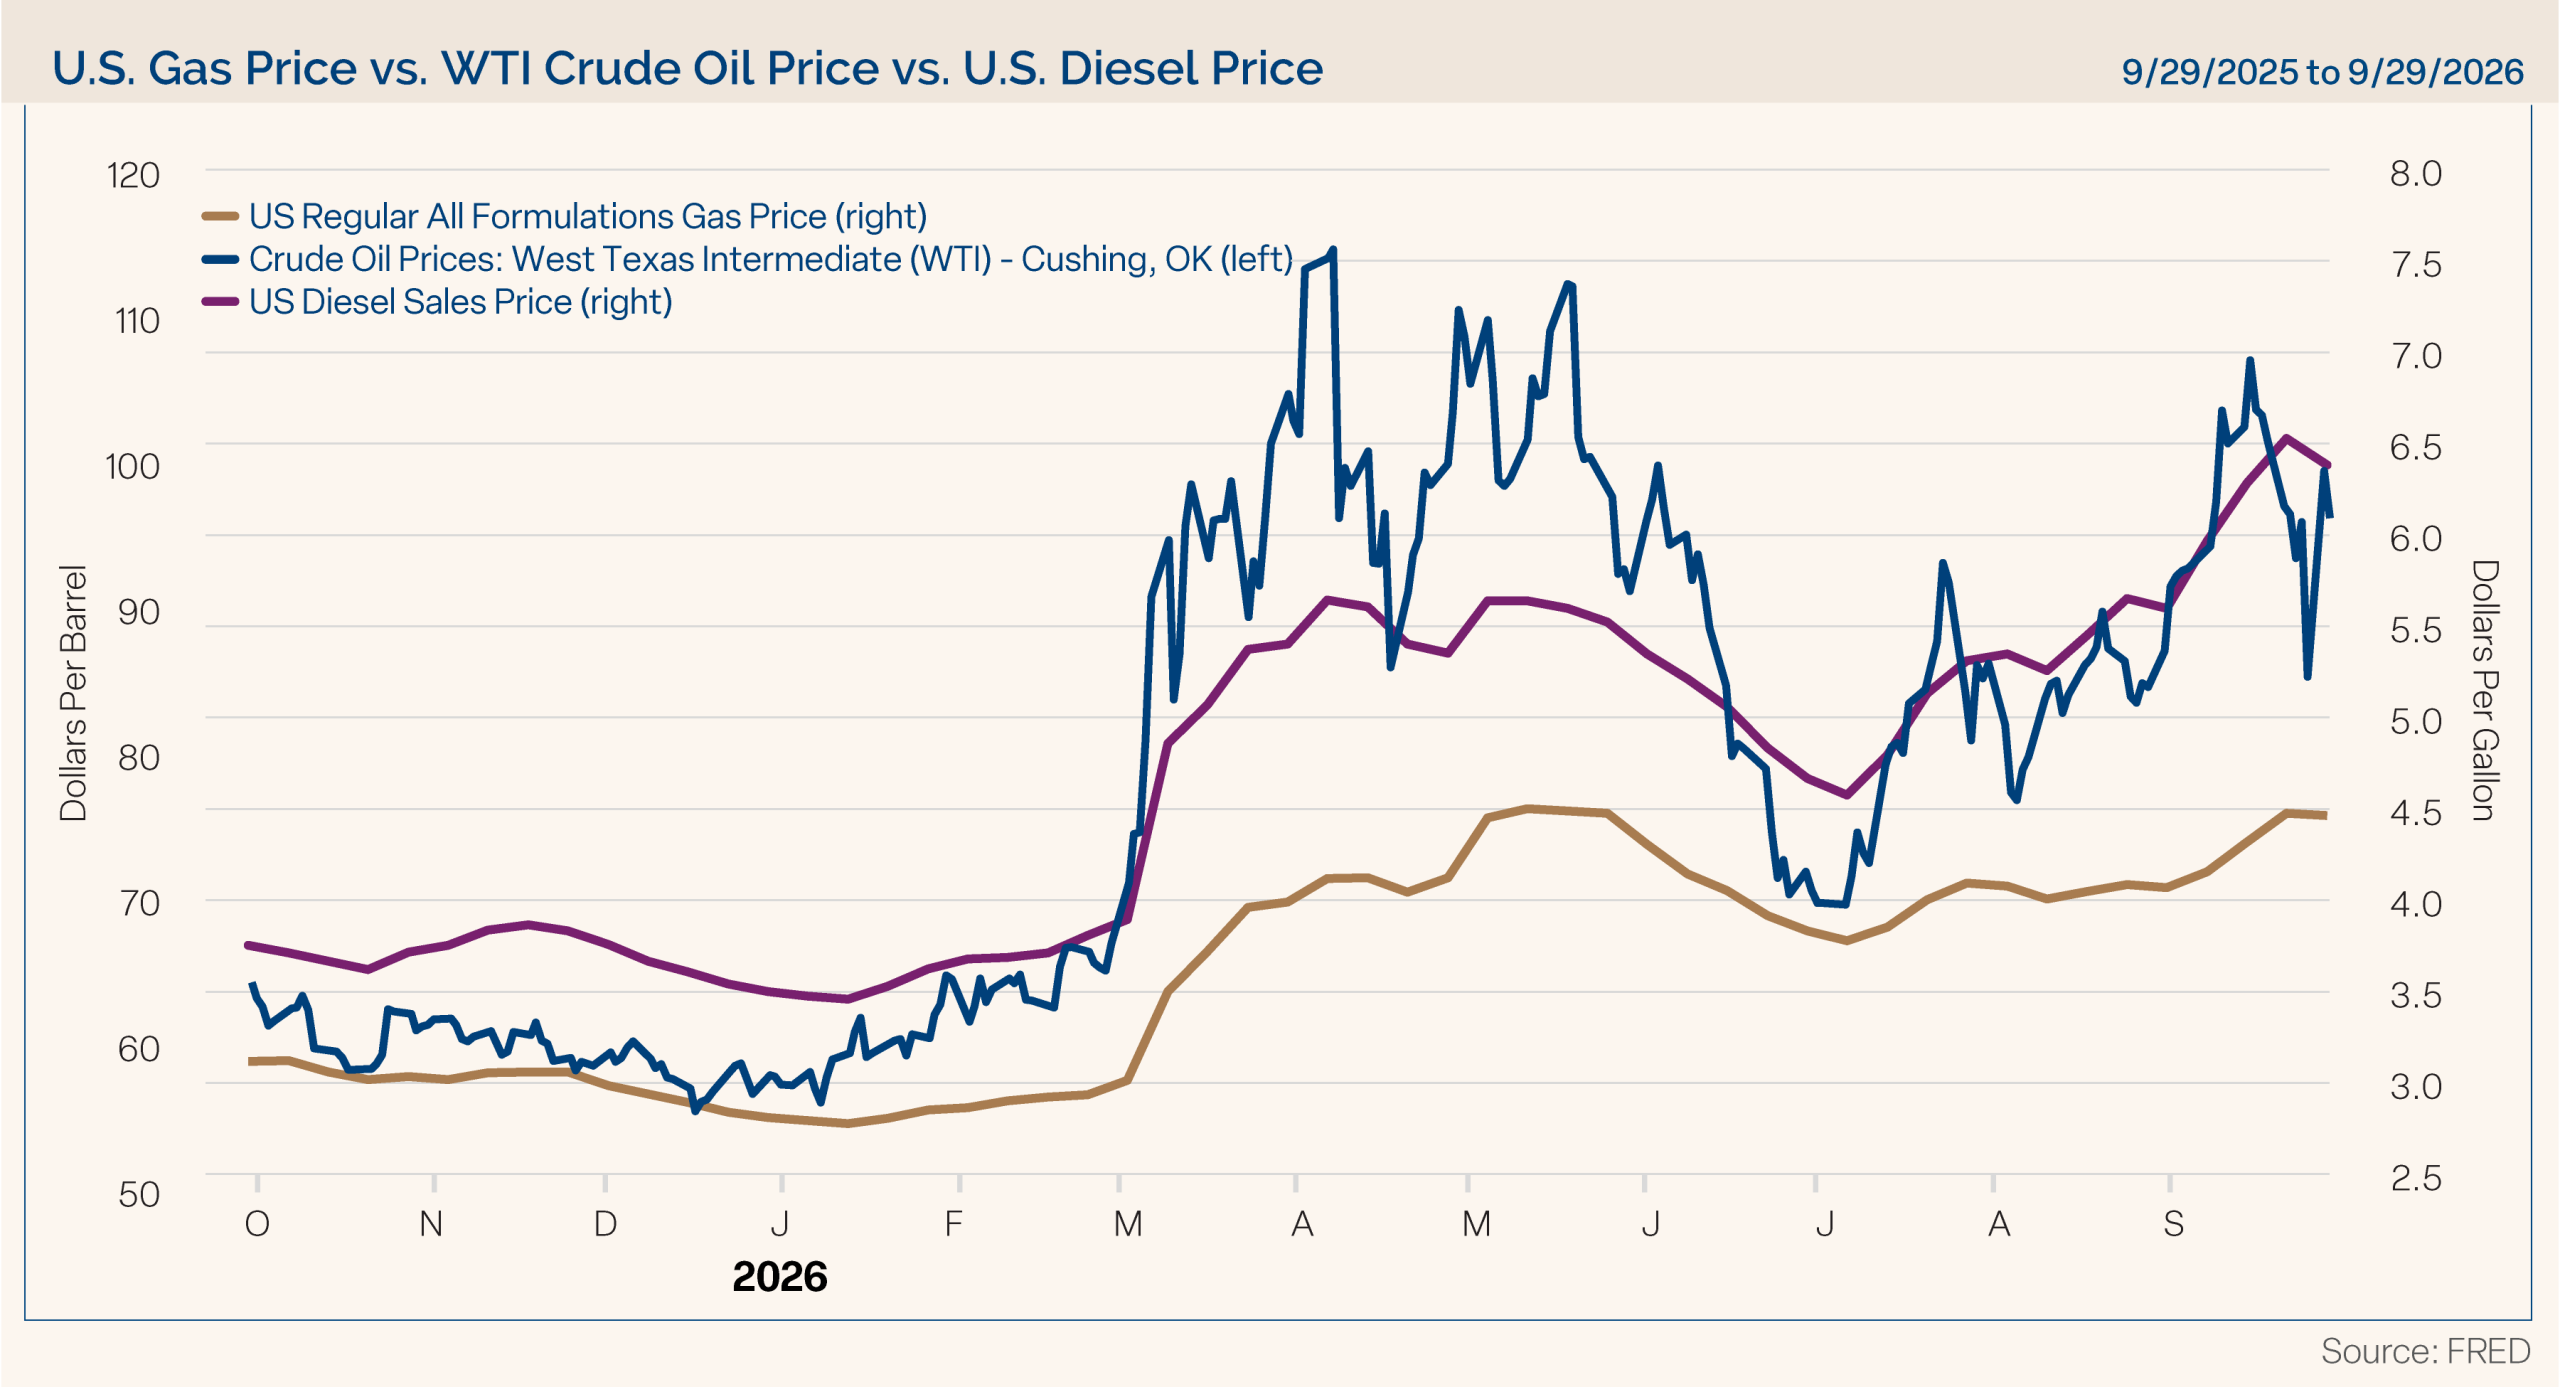
Economic data generally reflected growth, but the ongoing conflict with Iran, higher oil prices, sharply rising interest rates, and stubborn inflation continue to be potential headwinds. Gasoline prices rose throughout the month of September as negotiations with Iran appear to have hit a stalemate. Consumers can see these higher gas prices every time they fill up their car, and sentiment readings have slumped. Diesel prices rose to an all-time high in September, which directly impacts trucking costs and the transportation of many items, such as food products. The elevated pressure on these prices was likely one cause leading the Fed to increase rates in September for the first time in over three years. Chart 2 shows the increase in oil, gas, and diesel prices over the last year.
Chart 2
Inflation remains elevated. At the wholesale level, prices moved higher in August, but consumer inflation readings continue to reflect more persistently elevated, versus rising, prices. Clearly, it will be important to monitor whether wholesale prices push consumer prices higher in the months ahead. The Producer Price Index (PPI) rose 0.4% as expected, and the annual increase was 5.4%, which was 0.1% higher than estimates. The core PPI reading rose 0.2% compared to expectations of 0.3%, and the annual gain was in line with estimates of 4.6%. Both annual gains were above prior month’s levels.
Except for the core monthly reading, the Consumer Price Index (CPI) matched expectations across the board. The headline CPI was up 0.4% for the month and 3.4% for the year, while core CPI rose 0.3% for the month (expectations were 0.2%) and 2.4% for the year. The core reading was a modest improvement from the 2.5% annual gain through the prior month as the headline number remained the same at 3.4%.
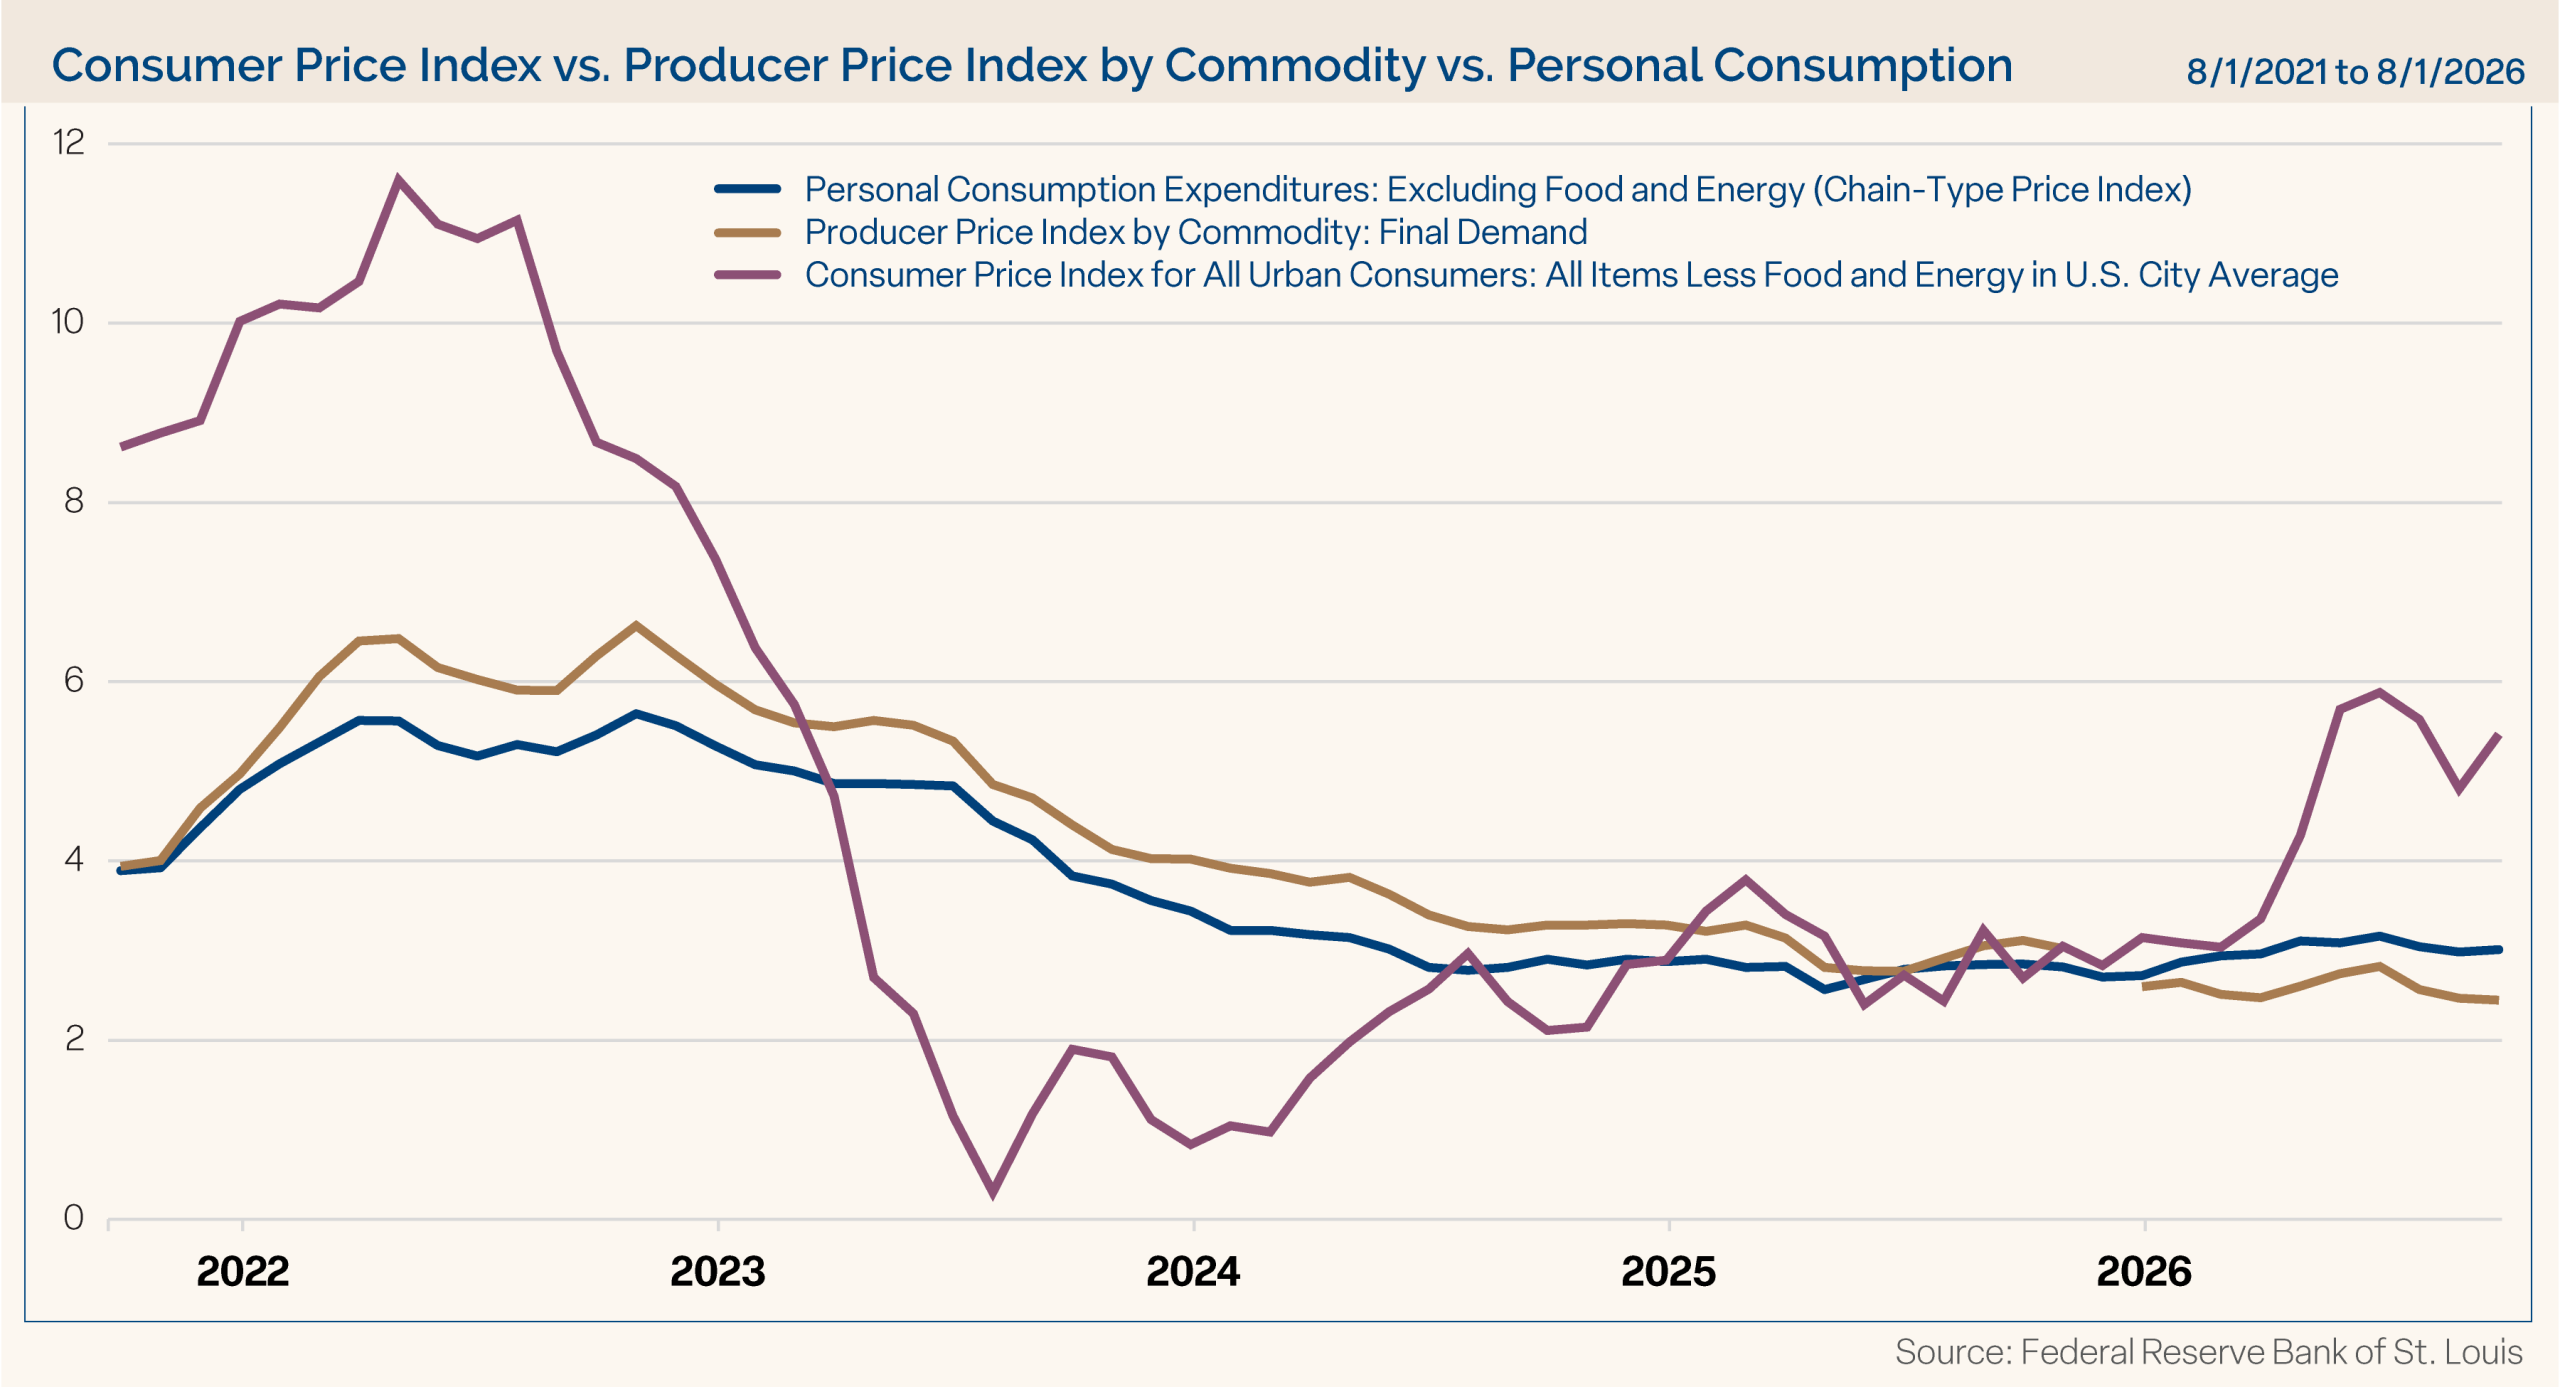
The Personal Consumption Expenditures (PCE) price index rose by 0.3% this month, matching estimates. The annual increase exceeded expectations at 3.4% and matched the prior month’s annual gain, which was revised lower. The core PCE reading (historically the Fed’s preferred measure of inflation) rose 0.2% for the month and 3.0% for the year. Both core PCE readings were better (lower) than expectations and the annual increase matched the revised lower reading from the prior month. Chart 3 shows the two consumer-based price indices (CPI and PCE) at a core level and the PPI at a headline level. Core consumer prices remain stubbornly elevated, while PPI has moved higher with rising energy prices. To this point, wholesale prices have not pushed up consumer inflation, but, in our opinion, this will need to be watched.
Chart 3
Broader economic data was solid in August reflecting ongoing economic progress. For eight months in a row, the Institute for Supply Management (ISM) Manufacturing Index was in growth territory at 54.6, but this was a modest miss compared to expectations of 55.2. The ISM Manufacturing Index was positive again in September at 54.5, but this was also modestly below expectations of 55.0. The ISM Non-Manufacturing Index, which covers the much larger service industries in the U.S. economy, surpassed expectations of 54.1 with a reading of 55.4, the strongest level since February. Recall for the ISM indices, readings above 50 represent expansion and below 50 reflect contraction.
After disappointing data in July, the labor market rebounded in August. Nonfarm payrolls rose by 162,000, easily surpassing expectations of 55,000. Importantly, the negative July reading that showed 23,000 jobs lost was revised to a gain of 21,000. The unemployment rate remained steady at 4.1%, as expected. While still solid, job openings declined from a level north of 7.3 million in July to just below 7.1 million in August, which missed estimates.
Consumer spending remained strong in August. Retail sales (ex auto and gas) rose by 1.2% for the month, surpassing expectations of 0.4%. While this reading excludes auto and gas prices, it is not inflation-adjusted so higher prices can impact this reading. Personal spending increased by 0.9% in August, as expected.
While consumers continued to spend, sentiment readings weakened. The preliminary University of Michigan Consumer Sentiment reading fell to 47.8 from 51.7 and missed expectations of 51.0. The Conference Board consumer confidence reading slumped to 81.9 from 88.6 and missed estimates of 89.0. This was the lowest reading for this index since 2014. Higher gas prices, rising interest rates, and the ongoing conflict in Iran are among the factors leading to poor confidence readings, but spending has continued to hold on and remain solid. We will watch whether the “soft” survey data leads into any weakening of the “hard” economic data we see from actual spending numbers.
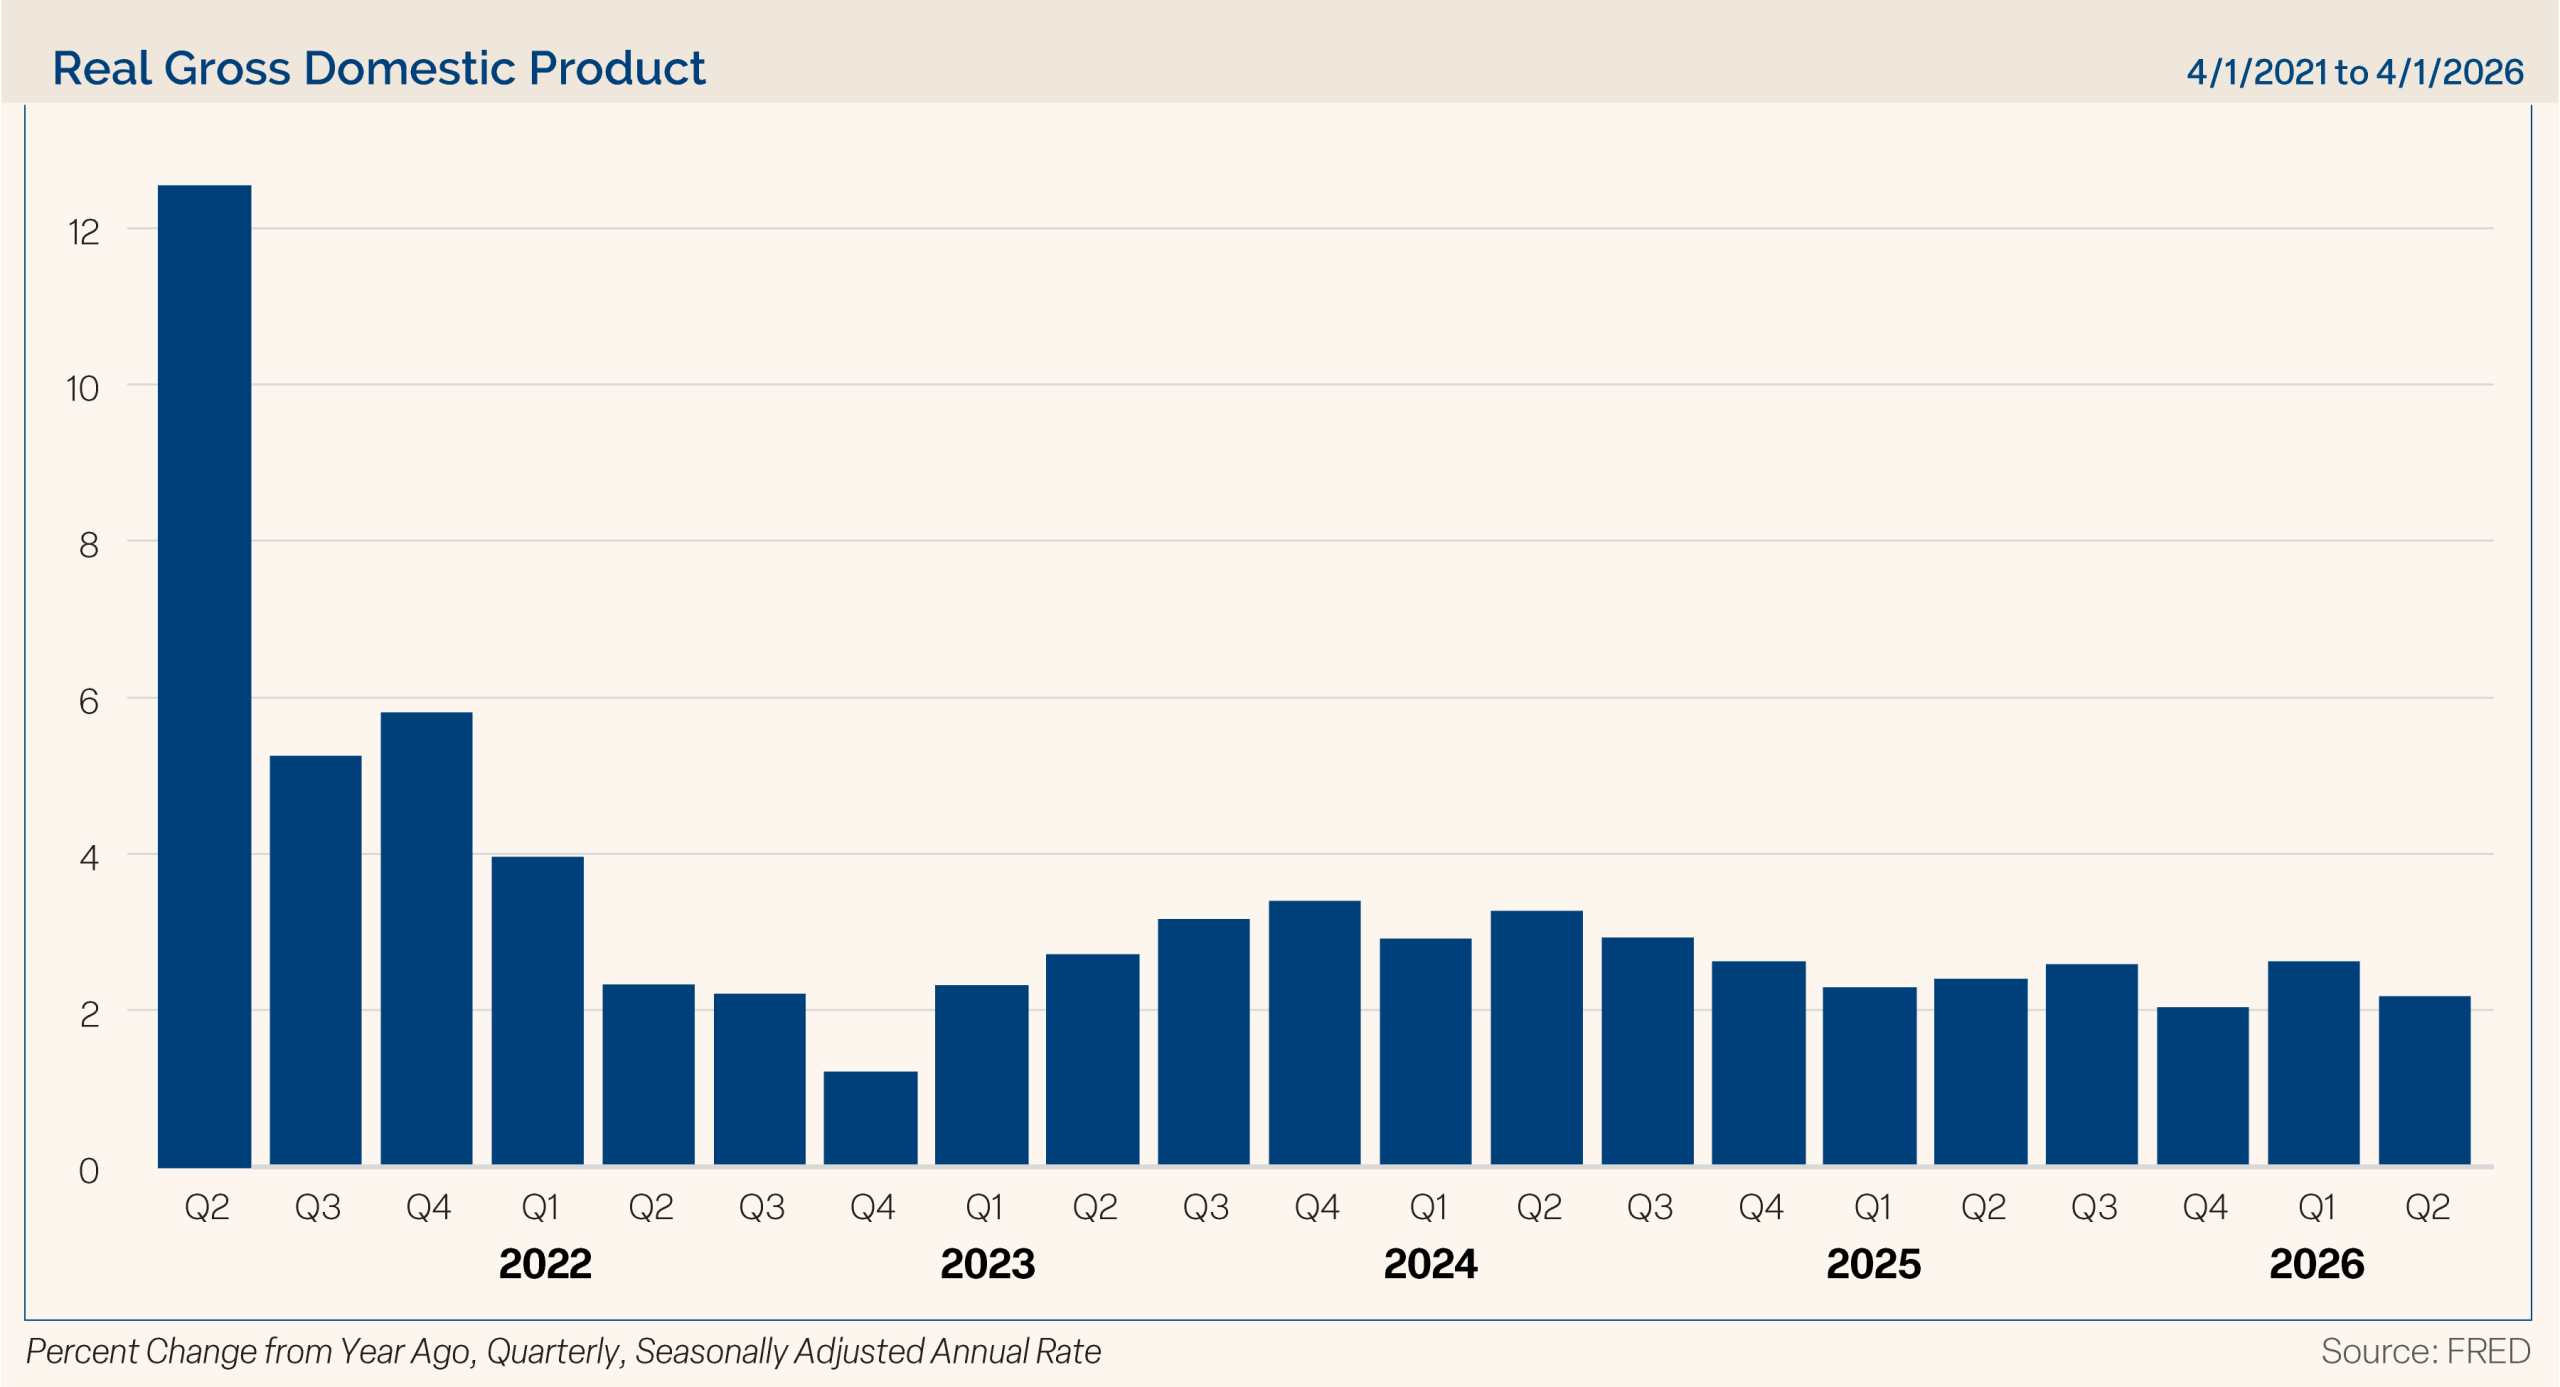
The final reading of Q2 GDP showed economic growth was much stronger than originally thought. After back-to-back 1.5% growth readings, the final Q2 number came in at a 2.2% annualized growth rate with the personal consumption component (another sign of household spending) being one area that was revised higher. The Atlanta Fed’s GDPNow forecast for Q3 shows an expected 3.7% annualized GDP growth rate (as of October 1, 2026). While this estimate tends to be high, it shows that ongoing data throughout the third quarter reflects solid underlying growth. Chart 4 shows the ongoing resiliency we have seen in the U.S. economy in recent years with steady economic growth.
Chart 4
In a month of significant news, the Federal Open Market Committee (FOMC) might have made the most noise in September. With solid economic activity as a backdrop and inflation that has been persistently above target levels for years, the FOMC unanimously decided to raise rates for the first time since 2023. Kevin Warsh, in his short stint as Fed Chair, has continuously expressed that he would rein in inflation, and his actions at the latest FOMC meeting saw the “rubber hit the road” with a rate hike. The market is currently expecting one additional hike in December and pricing in two more hikes in 2027 (per the CME FedWatch tool as of October 1, 2026). The market is still getting used to Warsh’s style, which differs from predecessors by not providing much guidance to the market. This could usher in a period of elevated volatility. It is important to note that stocks have historically done well when the Fed is raising rates slowly, which is what the market expectation is at this point.
With midterm elections looming, we would not be surprised by elevated market volatility as we head toward November. Strong earnings from corporate America continue to create a strong fundamental backdrop for the stock market, in our opinion. Rising rates have pressured the bond market, but we believe this has also created some of the best bond yield levels we have seen in decades. We need to monitor whether higher rates start to slow economic activity, which has been resilient to this point. The FOMC will take center stage in late October as it meets just ahead of the midterms. There is a lot of noise out there, but as always, we believe it is imperative for investors to stay focused on their long-term goals and not let short-term swings in the market, which could materialize at any time, derail them from their longer-term objectives.
Economic Data
| Event | Period | Estimate | Actual | Prior | Revised |
|---|---|---|---|---|---|
| ISM Manufacturing | Aug | 55.2 | 54.6 | 55.6 | — |
| ISM Services Index | Aug | 54.1 | 55.4 | 54.1 | — |
| Change in Nonfarm Payrolls | Aug | 55k | 162k | -23k | 21k |
| Unemployment Rate | Aug | 4.1% | 4.1% | 4.1% | — |
| Average Hourly Earnings YoY | Aug | 3.1% | 3.1% | 3.2% | — |
| JOLTS Job Openings | Aug | 7228k | 7079k | 7271k | 7335k |
| PPI Final Demand MoM | Aug | 0.4% | 0.4% | 0.0% | 0.1% |
| PPI Final Demand YoY | Aug | 5.3% | 5.4% | 4.7% | 4.8% |
| PPI Ex Food and Energy MoM | Aug | 0.3% | 0.2% | 0.2% | 0.3% |
| PPI Ex Food and Energy YoY | Aug | 4.6% | 4.6% | 4.2% | 4.3% |
| CPI MoM | Aug | 0.4% | 0.4% | 0.1% | — |
| CPI YoY | Aug | 3.4% | 3.4% | 3.4% | — |
| CPI Ex Food and Energy MoM | Aug | 0.2% | 0.3% | 0.2% | — |
| CPI Ex Food and Energy YoY | Aug | 2.4% | 2.4% | 2.5% | — |
| Retail Sales Ex Auto and Gas | Aug | 0.4% | 1.2% | -0.2% | -0.2% |
| Industrial Production MoM | Aug | 0.3% | 0.0% | 0.2% | — |
| Building Permits | Aug P | 1408k | 1394k | 1433k | __ |
| Housing Starts | Aug | 1320k | 1275k | 1239k | 1309k |
| New Home Sales | Aug | 616k | 684k | 607k | 643k |
| Existing Home Sales | Aug | 3.98m | 3.98m | 4.06m | — |
| Leading Index | Aug | 0.1% | -0.1% | 0.2% | — |
| Durable Goods Orders | Aug P | -0.3% | 0.0% | 1.1% | 0.9% |
| GDP Annualized QoQ | 2Q T | 55.0 | 51.0 | 55.2 | — |
| U. of Mich. Sentiment | Sept P | 51.0 | 47.8 | 51.7 | — |
| Personal Income | Aug | 0.5% | 0.2% | 0.4% | 0.3% |
| Personal Spending | Aug | 0.9% | 0.9% | 0.2% | 0.1% |
| S&P Cotality CS 20-City YoY NSA | July | 2.20% | 2.47% | 2.10% | 2.15% |
Disclosures
Forward looking statements cannot be guaranteed. Past performance is not indicative of future results. The opinions referenced are as of the date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. Material presented has been derived from sources considered to be reliable and has not been independently verified by us or our personnel. Nothing herein should be construed as a solicitation, recommendation or an offer to buy, sell or hold any securities, other investments or to adopt any investment strategy or strategies. Investors must make their own decisions based on their specific investment objectives and financial circumstances. Investing involves risk, including loss of principal.Clark Capital Management Group is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about Clark Capital Management Group’s advisory services can be found in its Form ADV and/or Form CRS, which are available upon request.
The manager utilizes a proprietary investment model to assist with the construction of the strategy and to assist the manager with making investment decisions. Investments selected using this process may perform differently than expected as a result of the factors used in the model, the weight placed on each factor, and changes from the factors’ historical trends. There is no guarantee that Clark Capital’s use of a model will result in effective investment decisions.
Fixed income securities are subject to certain risks including, but not limited to: interest rate (changes in interest rates may cause a decline in market value or an investment), credit, prepayment, call (some bonds allow the issuer to call a bond for redemption before it matures), and extension (principal repayments may not occur as quickly as anticipated, causing the expected maturity of a security to increase).
Non-investment-grade debt securities (high-yield/junk bonds) may be subject to greater market fluctuations, risk of default or loss of income and principal than higher-rated securities.
The value of investments, and the income from them, can go down as well as up and you may get back less than the amount invested.
Equity securities are subject to price fluctuation and possible loss of principal. Stock markets tend to move in cycles, with periods of rising prices and periods of falling prices. Certain investment strategies tend to increase the total risk of an investment (relative to the broader market). Strategies that concentrate their investments in limited sectors are more vulnerable to adverse market, economic, regulatory, political, or other developments affecting those sectors.
JOLTS is a monthly report by the Bureau of Labor Statistics (BLS) of the U.S. Department of Labor counting job vacancies and separations, including the number of workers voluntarily quitting employment.
The Core Consumer Price Index (CPI) is a measure of the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services.
The Core Producer Price Index (PPI) program measures the average change over time in the selling prices received by domestic producers for their output. The prices included in the PPI are from the first commercial transaction for many products and some services.
The PCE price index, released each month in the Personal Income and Outlays report, reflects changes in the prices of goods and services purchased by consumers in the United States.
References to market or composite indices, benchmarks or other measures of relative market performance over a specified period of time (each, an “index”) are provided for your information only. Reference to an index does not imply that the portfolio will achieve returns, volatility or other results similar to that index. The composition of the index may not reflect the manner in which a portfolio is constructed in relation to expected or achieved returns, portfolio guidelines, restrictions, sectors, correlations, concentrations, volatility or tracking error targets, all of which are subject to change. Investors cannot invest directly in an index.
The Dow Jones Industrial Average® (The Dow®), is a price-weighted measure of 30 U.S. blue-chip companies.
The index covers all industries except transportation and utilities.
The Bloomberg Barclays U.S. Municipal Index covers the USD-denominated long-term tax exempt bond market. The index has four main sectors: state and local general obligation bonds, revenue bonds, insured bonds and prerefunded bonds.
The Bloomberg US Treasury Index measures US dollar-denominated, fixed-rate, nominal debt issued by the US Treasury. Treasury bills are excluded by the maturity constraint, but are part of a separate Short Treasury Index.
The NASDAQ Composite is a stock market index of the common stocks and similar securities listed on the NASDAQ
stock market.
The S&P 500 measures the performance of the 500 leading companies in leading industries of the U.S. economy, capturing 80% of U.S. equities.
The S&P 500® Equal Weight Index (EWI) is the equal-weight version of the widely-used S&P 500. The index includes the same constituents as the capitalization weighted S&P 500, but each company in the S&P 500 EWI is allocated a fixed weight or 0.2% of the index total at each quarterly rebalance.
The University of Michigan Consumer Sentiment Index rates the relative level of current and future economic conditions. There are two versions of this data released two weeks apart, preliminary and revised. The preliminary data tends to have
a greater impact. The reading is compiled from a survey of around 500 consumers.
The Russell 1000 Index is a stock market index that tracks the highest-ranking 1,000 stocks in the Russell 3000 Index, which represent about 93% of the total market capitalization of that index.
The Russell 2000 Index is a small-cap stock market index that represents the bottom 2,000 stocks in the Russell 3000.
The Russell 3000 Index measures the performance of the 3,000 largest U.S. companies based on total market capitalization, which represents approximately 98% of the investable U.S. equity market.
Russell 1000 Growth Index tracks companies with higher price-to-book ratios, higher sales per share growth, and higher I/B/E/S forecast growth.
Russell 1000 Value Index tracks companies with lower price-to-book ratios and lower expected and historical growth rates. Russell’s value indexes focus more on dividend yield.
Nonfarm payrolls (NFPs) are the measure of the number of workers in the United States excluding farm workers and workers in a handful of other job classifications.
A municipal bond, commonly known as a muni, is a bond issued by state or local governments, or entities they create such as authorities and special districts.
The CBOE Volatility Index (VIX) is a real-time index that measures the expected volatility of the S&P 500 over the next
30 days.
The U.S. Treasury index is based on the recent auctions of U.S. Treasury bills. Occasionally it is based on the U.S. Treasury’s daily yield curve.
The 30 Year Treasury Rate is the yield received for investing in a US government issued treasury security that has a maturity of 30 years.
The Bloomberg Barclays U.S. Corporate High-Yield Index covers the U.S. dollar-denominated, non-investment grade, fixed-rate, taxable corporate bond market. Securities are classified as high-yield if the middle rating of Moody’s, Fitch,
and S&P is Ba1/BB+/BB+ or below.
The Bloomberg Barclays U.S. Credit Index measures the investment grade, U.S. dollar denominated, fixed-rate taxable corporate and government related bond markets.
The Bloomberg Aggregate Bond Index or “the Agg” is a broad-based fixed-income index used by bond traders and the managers of mutual funds and exchange-traded funds (ETFs) as a benchmark to measure their relative performance.
The Bloomberg US Trsy Bellwether 30Y is a U.S. Treasury debt obligation that has a maturity of 30 years.
The ISM Non-Manufacturing Index is an index based on surveys of more than 400 non-manufacturing firms’ purchasing and supply executives, within 60 sectors across the nation, by the Institute of Supply Management (ISM). The ISM Non-Manufacturing Index tracks economic data, like the ISM Non-Manufacturing Business Activity Index. A composite diffusion index is created based on the data from these surveys, that monitors economic conditions of the nation.
ISM Manufacturing Index measures manufacturing activity based on a monthly survey, conducted by Institute for Supply Management (ISM), of purchasing managers at more than 300 manufacturing firms.
The MSCI Emerging Markets Index captures large and mid cap representation across 27 Emerging Markets (EM) countries.
The MSCI ACWI ex USA Index captures large and mid cap representation across 22 of 23 Developed Markets (DM) countries (excluding the US) and 27 Emerging Markets (EM) countries*. With 2,359 constituents, the index covers approximately 85% of the global equity opportunity set outside the US.
The S&P CoreLogic Case-Shiller 20-City Composite Home Price NSA Index seeks to measures the value of residential real estate in 20 major U.S. metropolitan areas. The U.S. Treasury index is based on the recent auctions of U.S. Treasury bills. Occasionally it is based on the U.S. Treasury’s daily yield curve.
The Leading Economic Index provides an early indication of significant turning points in the business cycle and where the economy is heading in the near term.
In the United States, the Core Personal Consumption Expenditure Price (CPE) Index provides a measure of the prices paid by people for domestic purchases of goods and services, excluding the prices of food and energy.
The Conference Board’s Leading Indexes are the key elements in an analytic system designed to signal peaks and troughs in the business cycle. The leading, coincident, and lagging economic indexes are essentially composite averages of several individual leading, coincident, or lagging indicators. They are constructed to summarize and reveal common turning point patterns in economic data in a clearer and more convincing manner than any individual component – primarily because they smooth out some of the volatility of individual components.
Gross domestic product (GDP) is the standard measure of the value added created through the production of goods and services in a country during a certain period.
