
Producer and consumer prices indices came in a little hotter last week, paving the way for the Federal Reserve to hike interest rates for the first time since July 2023. As expected, the Fed obliged and lifted overnight rates by 0.25% to a range of 3.75% to 4% today. The market has been pricing in a rate hike for some time, and the market wants the Fed to hike more than just once. Fed funds futures are pricing in one more hike this year in December and potentially two more hikes next year. The move to hike was unanimous and there were no dissents, in stark contrast to the three dissents in the July FOMC meeting. No policymaker favored staying on hold, and in our opinion, that adds to the decisiveness of the rate hike.
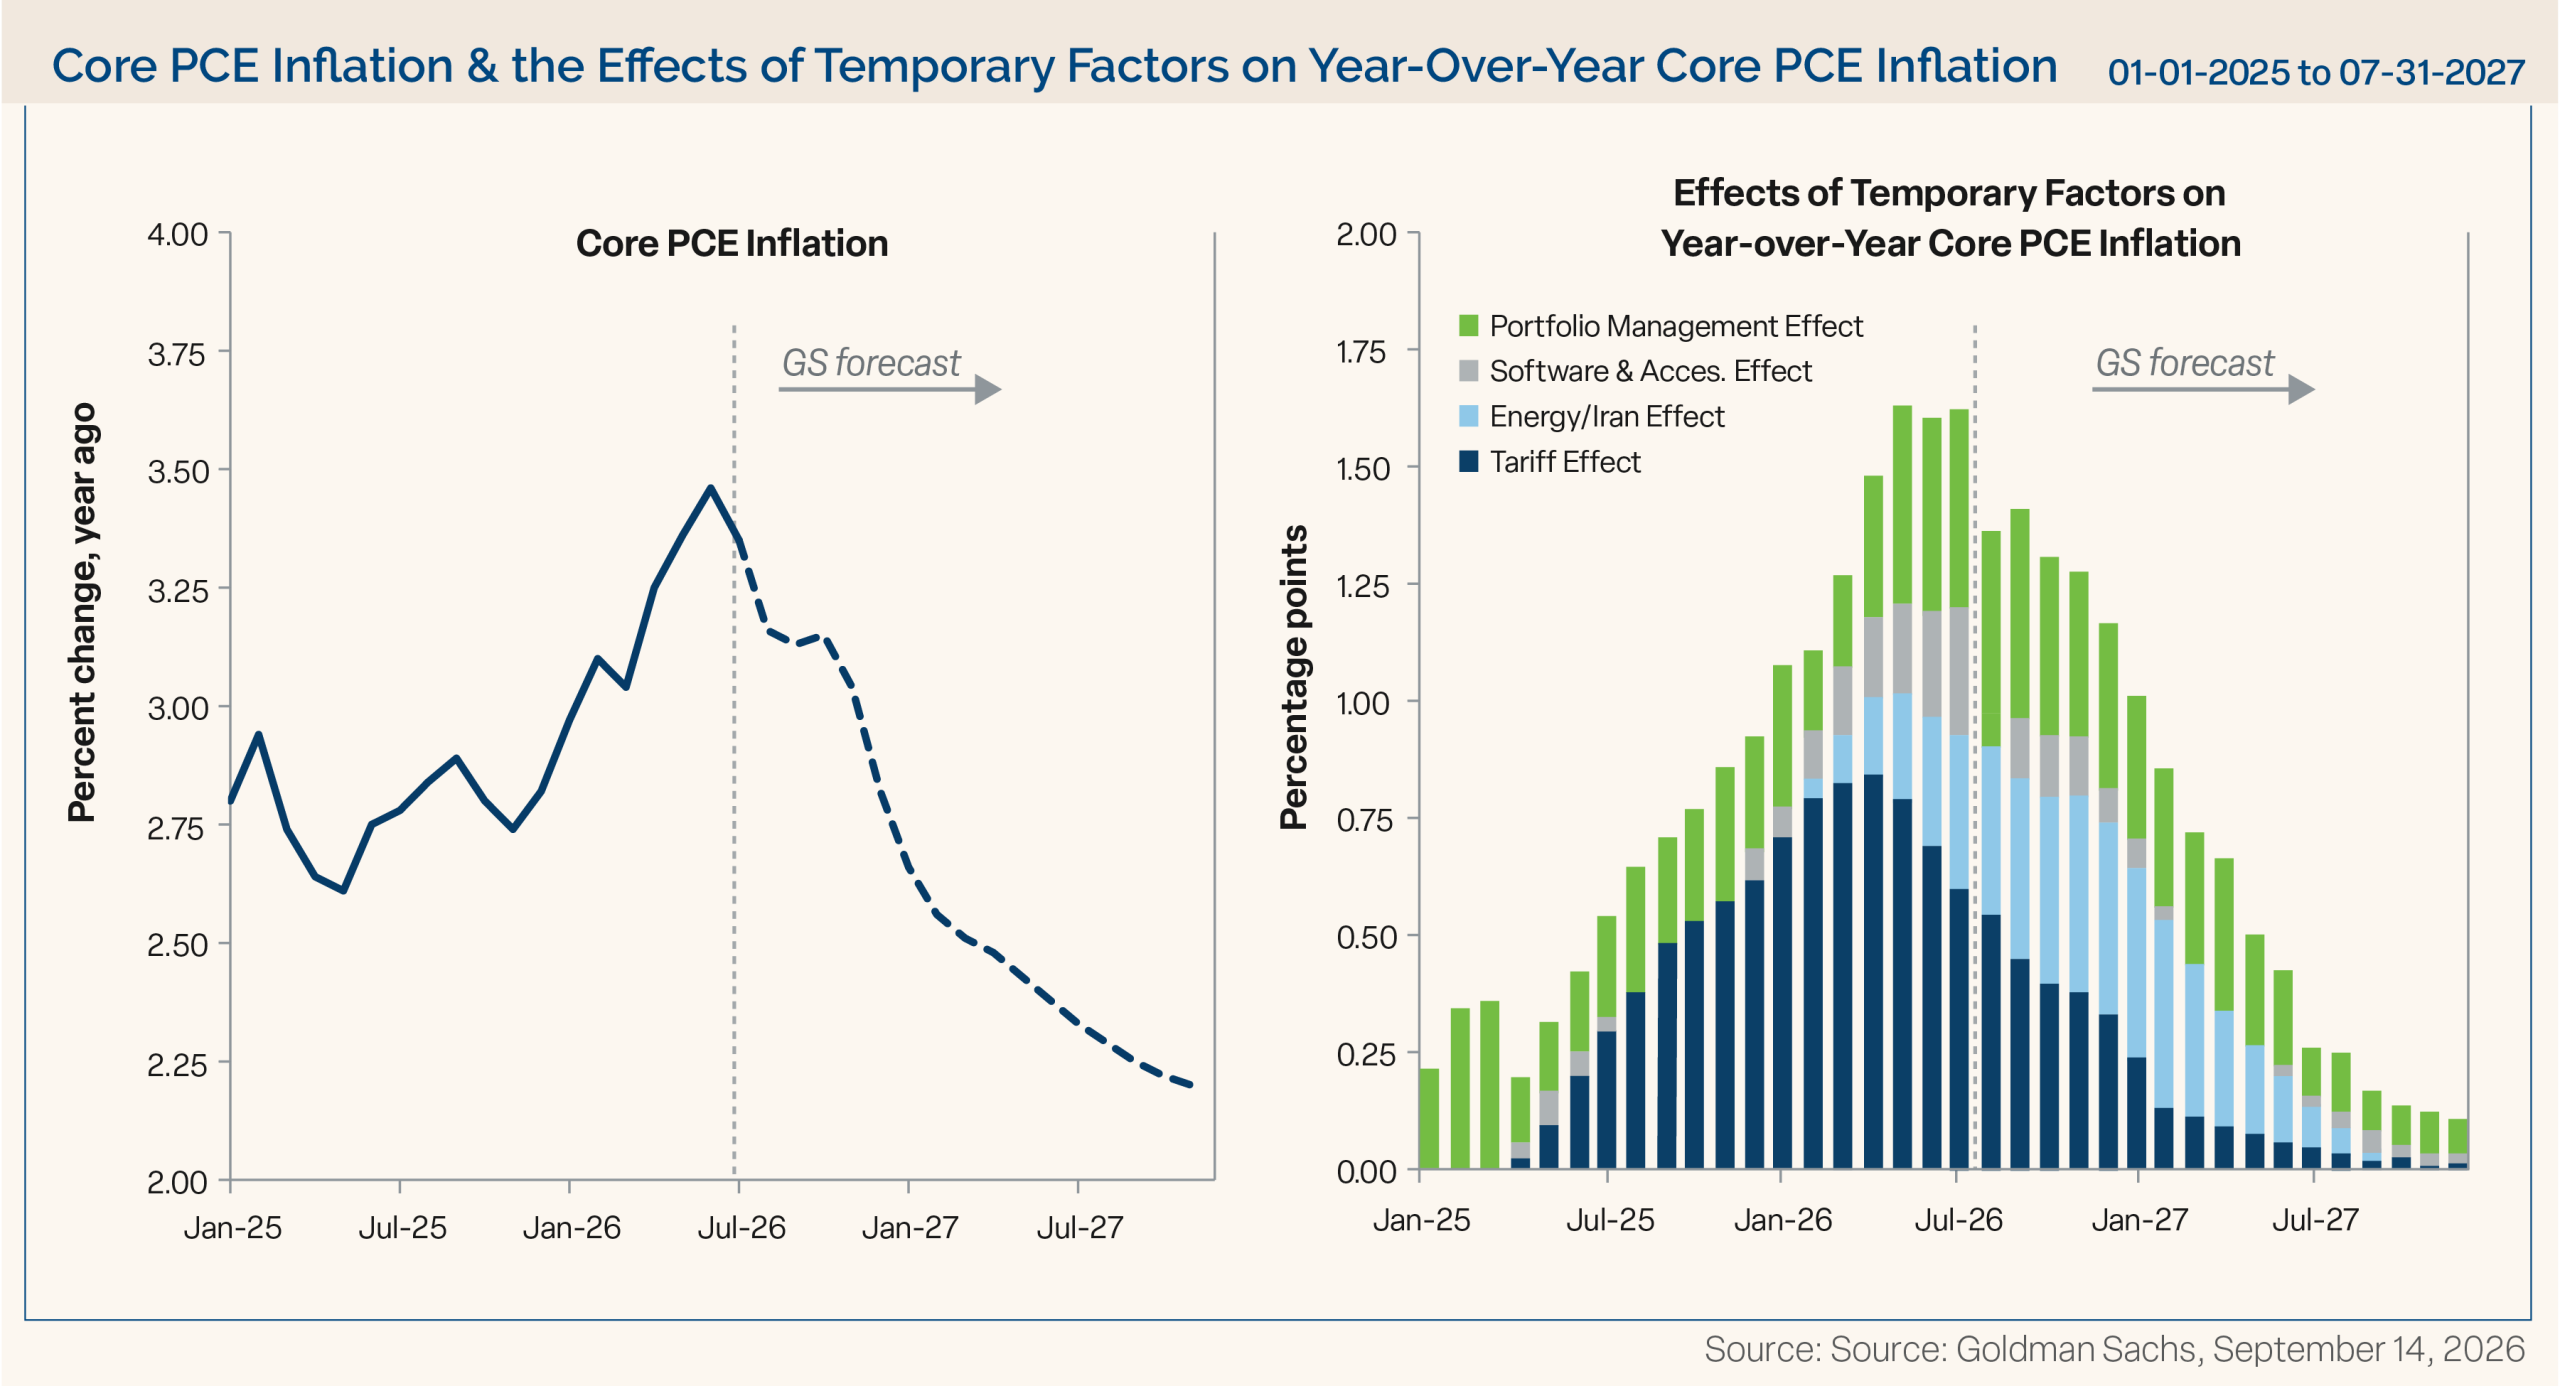
The Fed is fighting a credibility problem. Inflation has been above its 2% target for 65 straight months, as measured by its preferred gauge, the Core PCE Index, which currently sits at 3.3% year over year. The FOMC cut the fed funds rate the equivalent of four times in 2024 and three times in 2025 for a total reduction of 175 basis points (bps). During that same period, the 10-year Treasury yield rose from 3.7% to 5% yesterday. The bond vigilantes have not believed the Fed was serious about bringing inflation down to target. The Fed’s statement said, “Today’s policy action will support a timelier return to the committee’s 2% goal.”
The dot plot of rate projections is more hawkish than most expected. It shows 16 of 18 officials expect another rate hike this year, and eight officials see an additional hike in 2027. In addition, the Fed sees core inflation at 3.4% by the end of this year along with GDP growth of 2.3%, slightly higher than their previous GDP forecast.
In our opinion, hiking rates into a supply shock is not what the Fed wants to be doing, but the market forced its hand. The Fed’s policy tools have historically been ineffective in dealing with supply shocks and are geared toward either increasing or decreasing demand. In this case, hiking rates with the cost of oil over $100/barrel does nothing to increase supply and likely does nothing to curtail demand either.
With inflation running above target, Goldman Sachs recently highlighted that almost all the inflation overshoot is due to fading, one-time factors, such as:
- Portfolio management costs — fees rising alongside the rising stock market
- Software and computer accessories — a nine-standard-deviation overshoot in memory chip prices
- Energy costs — driven by the war in Iran
- Tariffs
As those temporary effects roll off over the next six months, Goldman Sachs expects overall inflation to trend near the Fed’s target.
Projections or other forward looking statements regarding future financial performance of markets are only predictions and actual events or results may differ materially
As mentioned above, the 10-year Treasury note yield is pushing near 5%. The last time it tested the 5% zone was October 2023. Yields peaked at that level, and shortly thereafter the S&P 500 bottomed and began to move higher. History doesn’t repeat, but it often rhymes. We are in the midst of an earnings-driven bull market. We believe a 25 bps hike is not going to kill corporate earnings or the bull market.
Let’s see if the Fed threaded the needle of regaining some credibility and settling the markets’ nerves over the recent rise in Treasury yields. We believe stability in long-term rates would show the Fed is regaining credibility.
As always, we think it is important for investors to stay focused and not let short-term swings in the market derail them from their longer-term objectives.
The opinions referenced are as of the date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. There is no guarantee of the future performance of any Clark Capital investments portfolio. Material presented has been derived from sources considered to be reliable and has not been independently verified by us or our personnel. Nothing herein should be construed as a solicitation, recommendation or an offer to buy, sell or hold any securities, other investments or to adopt any investment strategy or strategies. For educational use only. Investors must make their own decisions based on their specific investment objectives and financial circumstances. Past performance does not guarantee future results.
References to market or composite indices, benchmarks or other measures of relative market performance over a specified period of time (each, an “index”) are provided for your information only. Reference to an index does not imply that the portfolio will achieve returns, volatility or other results similar to that index. The composition of the index may not reflect the manner in which a portfolio is constructed in relation to expected or achieved returns, portfolio guidelines, restrictions, sectors, correlations, concentrations, volatility or tracking error targets, all of which are subject to change. Investors cannot invest directly in an index.
The PCE price index, released each month in the Personal Income and Outlays report, reflects changes in the prices of goods and services purchased by consumers in the United States.
Clark Capital Management Group, Inc., is an independent investment adviser registered under the Investment Advisers Act of 1940, as amended. Registration does not imply a certain level of skill or training. More information about Clark Capital, including investment strategies, fees and objectives, can be found in its Form ADV and/or Form CRS, which are available upon request.