
The Federal Reserve met today and left overnight rates unchanged, as expected. Heading into today’s Federal Open Market Committee (FOMC) meeting, there was less than a 10% probability priced into the markets of a rate hike, so nothing surprising there. The committee left rates unchanged and reiterated their commitment to containing inflation. The Fed noted that inflation remains elevated, and the official statement read, “The accumulation of more information will help the committee determine the policy stance appropriate to ensure a timely return of inflation to the committee’s 2% goal. The committee will deliver price stability.” The FOMC voted 10-2 in favor of holding steady. Lisa Cook and Cleveland Fed President Beth Hammack dissented, instead preferring to raise rates by a quarter percentage point.
Of note during Chair Warsh’s press conference, he signaled that the schedule of FOMC meetings will change next fall. The FOMC will keep eight meetings as usual, but one will be a strategy meeting and seven will be live policy decision meetings regarding interest rates. In 2028, two will be strategy meetings and six will be policy meetings.
Looking into the future, odds of a rate hike now stand at 87% for the December 9 FOMC meeting. The market is still pricing in three more rate hikes in December, March, and September. Whether those hikes pan out depends upon the future path of inflation. After the December FOMC meeting, the Fed will release its Summary of Economic Projections detailing their updated forecast and potential interest rate path for 2027.
Now that we are past the Fed decision, all eyes shift to the earnings season and next week’s midterm elections. Earnings season is in full swing, and off to a good start, which has buoyed the market over the past several sessions. This week alone, 36% of the S&P 500 reported, including Alphabet, Microsoft, Intel, and Amazon. Overall, 83% of the companies that have already reported have beaten expectations. Blended year-over-year earnings for companies that have reported and estimates for those that have not yet reported are running a 30% growth rate.
As far as midterm elections go, the House is forecast to flip in favor of the Democrats, and the Senate is a toss-up. Either way we are likely to have gridlock over the final two years of the Trump administration. We have always advocated that investors should not let their political persuasions interfere with their investments. They should instead focus on corporate and economic fundamentals. We will get a first look at third quarter GDP tomorrow. Expectations are for the economy to have posted 3.2% real GDP growth, accelerating from 2.5% and 2.2% in the first and second quarters. Next week we will get reports on the manufacturing and service sides of the economy, both firmly in expansion territory, and then the employment report which is expected to show an economy that added 55,000 jobs with a historically low 4.2% unemployment rate.
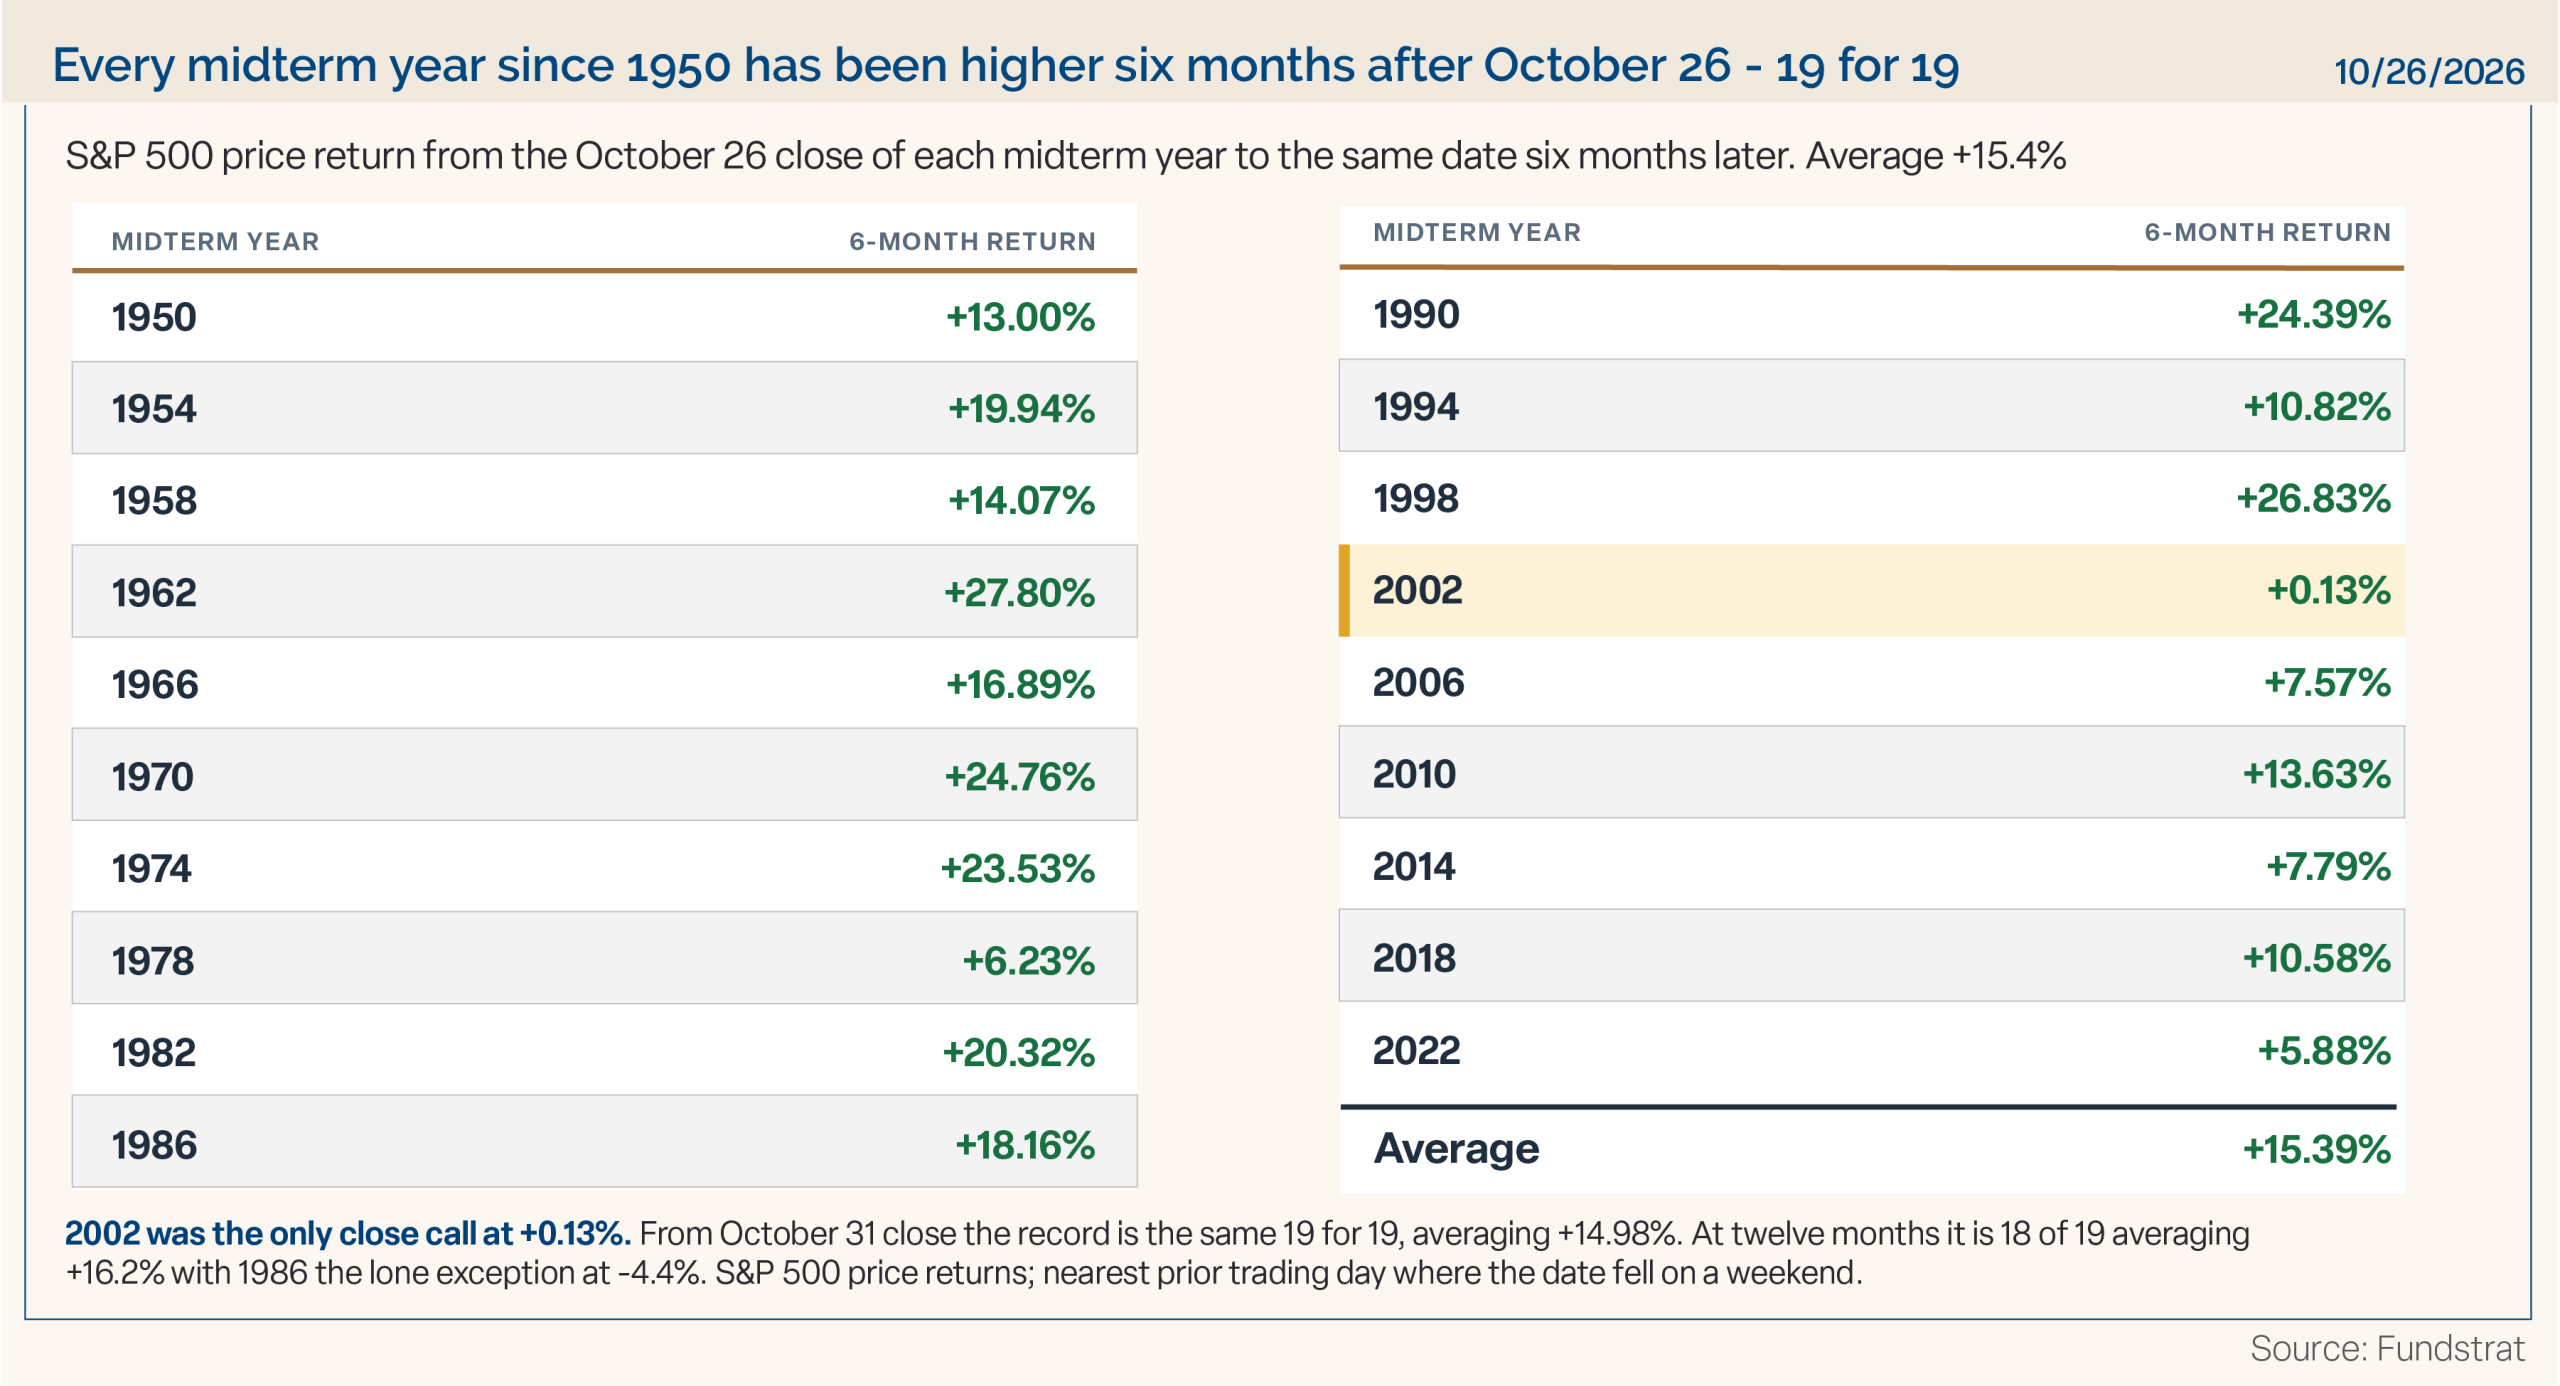
History suggests the market is now entering the strongest seasonal period of the four-year presidential cycle. Since 1950, the period coming off the October lows in midterm election years, the S&P 500 has risen over double the non-midterm year average in the following six months. See table below.
The opinions referenced are as of the date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. There is no guarantee of the future performance of any Clark Capital investments portfolio. Material presented has been derived from sources considered to be reliable and has not been independently verified by us or our personnel. Nothing herein should be construed as a solicitation, recommendation or an offer to buy, sell or hold any securities, other investments or to adopt any investment strategy or strategies. For educational use only. Investors must make their own decisions based on their specific investment objectives and financial circumstances. Past performance does not guarantee future results.
References to market or composite indices, benchmarks or other measures of relative market performance over a specified period of time (each, an “index”) are provided for your information only. Reference to an index does not imply that the portfolio will achieve returns, volatility or other results similar to that index. The composition of the index may not reflect the manner in which a portfolio is constructed in relation to expected or achieved returns, portfolio guidelines, restrictions, sectors, correlations, concentrations, volatility or tracking error targets, all of which are subject to change. Investors cannot invest directly in an index.
Clark Capital Management Group, Inc., is an independent investment adviser registered under the Investment Advisers Act of 1940, as amended. Registration does not imply a certain level of skill or training. More information about Clark Capital, including investment strategies, fees and objectives, can be found in its Form ADV and/or Form CRS, which are available upon request.