


Growth Slid, Value Led, and Bonds Rallied
HIGHLIGHTS
- Stocks: The AI trade, which led the market in September, stumbled in October. Growth stocks struggled for the month while other equity areas rebounded. Large-cap value continued to stand out year to date.
- Bonds: Yields fell rather dramatically in October after spiking higher in September. The 10-year U.S. Treasury closed September at 5.29%, but it fell to 4.94% to end October. Bond prices got a much-needed reprieve and advanced.
- U.S. Economy: The economy continued to broadly reflect growth. The initial Q3 GDP reading was the best in a year and the Atlanta Fed’s GDPNow estimate for Q4 growth stands at 3.7% (as of November 2, 2026).
- Federal Reserve: No change in October after the first rate increase in over three years in September. However, the market is pricing in a rate hike at the final FOMC meeting of 2026 in December.
Equity Markets
After being one of the few areas of strength in September, large-cap growth stocks struggled in October. Value companies continued to exhibit clear leadership for the year. Small-cap stocks advanced modestly in October and held on to solid year-to-date gains. See Table 1 for October, Q3, and YTD returns.
Table 1 | Equity Markets
| Index | Oct. 2026 | Q3 | YTD |
|---|---|---|---|
| S&P 500 | -0.87% | 2.30% | 11.77% |
| S&P 500 Equal Weight | 5.00% | -1.87% | 15.53% |
| DJIA | 1.76% | -2.34% | 9.08% |
| Russell 3000 | -0.64% | 1.41% | 11.71% |
| Russell 1000 Growth | -6.09% | 0.92% | -0.17% |
| Russell 1000 Value | 4.38% | 2.61% | 24.50% |
| NASDAQ Comp. | -5.28% | 2.61% | 9.95% |
| Russell 2000 | 0.58% | -7.23% | 14.37% |
| MSCI ACWI ex U.S. | -2.81% | 0.48% | 11.01% |
| MSCI Emerging Mkts Net | -8.05% | -0.37% | 13.45% |
The Russell 1000 Growth and Nasdaq Composite indices flipped from their market-leading performance in September to the weakest domestic results in October. In a remarkable shift back to the leadership, we have seen for most of 2026, large-cap value outperformed large-cap growth by more than 1000 basis points (bps) for the month (as measured by the Russell 1000 Value and Growth indices, respectively). Year to date, the Russell 1000 Value Index is up just shy of 25%, while the Russell 1000 Growth Index slipped into the red after October’s decline. Also reflecting broader progress in the stock market for the month, the equal-weighted S&P 500 Index gained 5%, while the headline market-cap weighted S&P 500 Index fell. We have frequently said that the S&P 500 Index is much more of a large-cap growth and tech weighted index these days, and returns in October reflected this dynamic. Emerging market stocks came under significant pressure. Not only did the technology trade reverse, which impacts tech-heavy markets like South Korea, but surprise election results in Brazil put pressure on that stock market, as well.
One consistent narrative supporting the stock market in 2026 has been very strong earnings growth. Earnings are expected to grow around 30% in 2026 and in the mid-teens in 2027. From a valuation perspective, the stock market is cheaper today than where we began the year. Estimates are subject to revision, but we are at a point in the market cycle where earnings growth has been accelerating and supporting gains in the stock market. We understand that earnings will eventually slow from these strong levels, but we have yet to see that slowdown develop. Furthermore, valuations are not extreme and seem broadly reasonable. The fundamental backdrop of strong earnings continues to keep us constructive on the stock market through the balance of 2026 and into 2027, but we are mindful that higher rates could become a headwind to the stock market and be more competition for investor dollars with rates at levels not seen in years.
Fixed Income
The rise in the 10-year U.S. Treasury was unrelenting in the third quarter, but October saw relief as yields fell rather dramatically. The 10-year yield closed September at 5.29%, but it slid to end October at 4.94%. The 30-year went from 5.64% to 5.31%. The drop in rates created a constructive backdrop for bonds and performance rebounded in October. See Table 2 for October, Q3, and YTD bond index returns.
Table 2 | Fixed Income Markets
| Index | Oct. 2026 | Q3 | YTD |
|---|---|---|---|
| Bloomberg U.S. Agg | 2.44% | -3.51% | -0.54% |
| Bloomberg U.S. Credit | 2.15% | -3.83% | -0.93% |
| Bloomberg U.S. High Yld | 0.30% | -1.82% | 0.40% |
| Bloomberg Muni | 3.85% | -6.35% | -0.48% |
| Bloomberg 30-year U.S. TSY | 5.53% | -8.74% | -2.98% |
| Bloomberg U.S. TSY | 2.36% | -3.04% | -0.47% |
After a challenging third quarter, bond returns rebounded in October. Remarkably, outside of the 30-year U.S. Treasury Index, returns in October pushed all the indices on Table 2 to below a -1.0% decline for the year with high yield still positive. For clients with individual bond portfolios, we own the bonds themselves. Bond prices might fluctuate, but we can make the decision to hold a bond, collect the coupon payments, and receive par value at maturity, assuming it doesn’t default. As an active manager, we might sell bonds before they mature if we find what we believe are better opportunities for our clients, but we can also just hold onto those bonds in volatile environments like we have recently experienced.
We maintain our longstanding position favoring credit versus pure rate exposure, which is especially important in a volatile interest rate environment. We believe the role bonds play in a portfolio, to provide stable cash flow and to help offset the volatility of stocks in the long run, has not changed. With uncertainty ahead, we believe having an active bond management approach makes sense. Furthermore, rates are elevated and provide investors with attractive opportunities not seen in some time.
Economic Data Highlights and Outlook
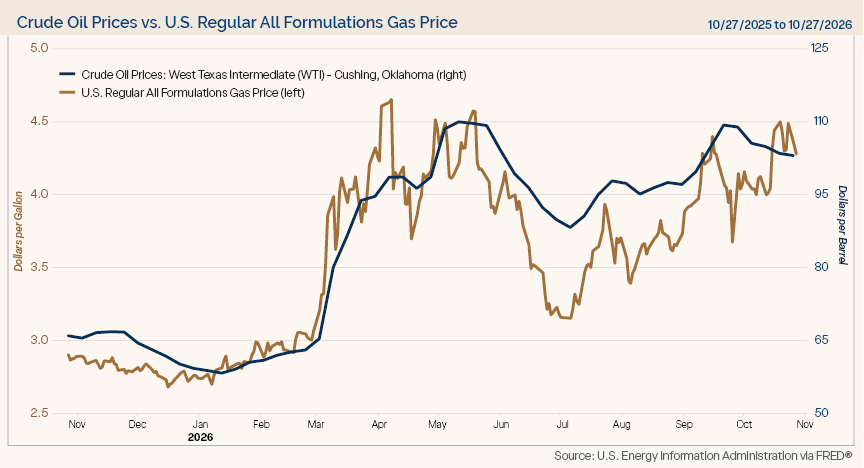
Economic data generally reflected growth in the U.S. economy. However, the ongoing conflict with Iran, higher oil prices, elevated interest rates, and stubborn inflation continue to be potential headwinds. Oil and, subsequently, gas prices remained elevated during most of October, which seems to be a key frustration to consumers. See Chart 1 reflecting higher oil and gas prices.
Chart 1
Consumer Sentiment
The preliminary University of Michigan Consumer Sentiment Index for October fell to 46.3 from 48.1 and missed expectations of 47.6. Although the final reading was revised higher to 48, it marked the second lowest reading in the history of this index going back to the early 1950s. Affordability, driven in part by higher gas prices, food costs, and elevated interest rates, continues to be a primary concern of consumers. Ironically, a better-than-expected personal consumption component from the advance Q3 GDP report helped economic growth expand at a faster annualized rate than expected. Consumers have sounded gloomy in sentiment surveys all year, yet they have kept spending, and that spending has supported the economy.
Inflation
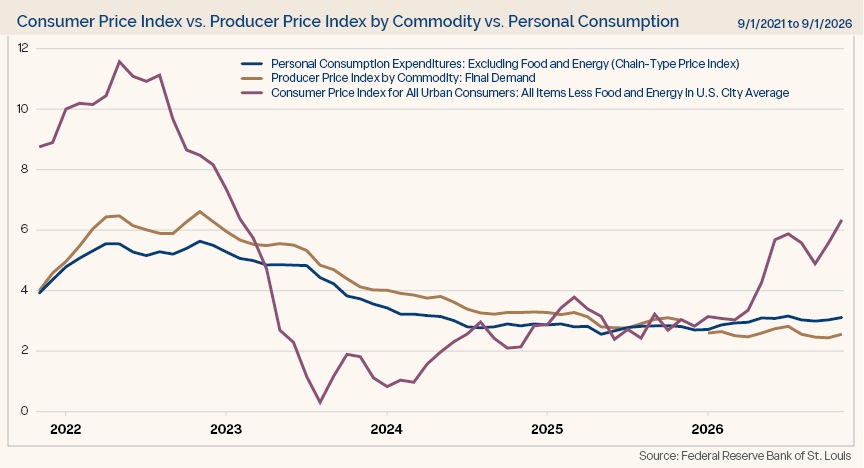
Inflation remains elevated and readings reflected general moves higher in prices in September. The Producer Price Index (PPI) rose 1.3% in September, more than double the expected increase of 0.6%. The annual increase was 6.3%, which was just under a full percentage point higher than expectations of 5.4%. The core PPI reading rose 0.7%, once again more than double expectations of 0.3%, and the annual gain of 5.0% was above estimates of 4.4%. The Consumer Price Index (CPI) rose 0.6% as expected and the annual gain of 3.7% was 0.1% higher than expectations. The core CPI rose 0.3% versus the expected 0.2% and the annual gain of 2.6% was also 0.1% higher than expected. The Personal Consumption Expenditures (PCE) price indices matched expectations across the board but still showed higher prices. The headline PCE index increased 0.5% in September and 3.6% for the year, while the core reading rose 0.3% for the month and 3.1% on an annual basis. Chart 2 shows the two consumer-based price indices (CPI and PCE) at a core level and the PPI at a headline level. Core consumer prices remain stubbornly elevated, while PPI has moved higher with rising energy prices. To this point, wholesale prices have not meaningfully increased consumer prices, but this will need to be watched
Chart 2
Manufacturing
Broader economic data was solid in September reflecting ongoing economic progress. For all of 2026, the Institute for Supply Management (ISM) Manufacturing Index has been in growth territory. At 54.5 in September, this index came up shy of expectations of 55.0 and was modestly lower than the prior month level of 54.6. However, the reading for October showed another month of expansion at 55.5, which beat estimates of 54.5. The ISM Services Index, which covers the much larger service industries in the U.S. economy, just missed expectations of 55.0 in September with a reading of 54.9, and the reading was lower than August’s mark. Recall for the ISM indices, readings above 50 represent expansion and below 50 reflect contraction.
Job Market
The back-and-forth nature of the job market continued with a disappointing reading in September after a better-than-expected number in August. Nonfarm payrolls rose by only 29,000, well short of the expected 90,000. The initial reading of 162,000 new jobs in August was reduced to 133,000. The unemployment rate ticked higher in September to 4.2% compared to estimates and the prior mark of 4.1%. Job openings increased to just over 7.5 million in September, an unexpected rise compared to expectations and the prior month’s level at just below 7.2 million.
Retail sales and spending
Retail sales (ex auto and gas) rose by 0.2% in September, as expected. While this reading excludes auto and gas prices, it is not inflation-adjusted so higher prices can impact this reading. A separate reading on personal spending increased by 0.5% in September, which was 0.1% lower than the expected 0.6% monthly gain. Consumers continued to spend despite weak sentiment readings.
Gross Domestic Product (GDP)
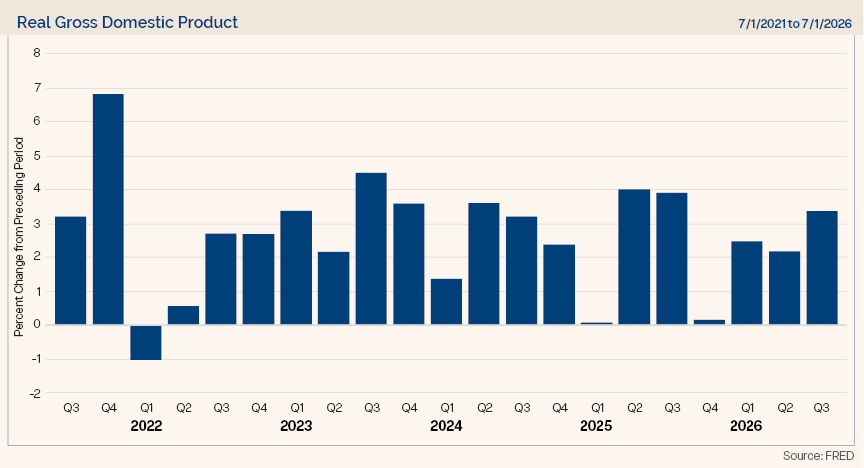
The advanced (or initial) reading of Q3 GDP growth was better than expected. At a 3.4% annualized growth rate, the reading was the strongest in a year and was led by gains in investment, consumer, and government spending. The personal consumption component of GDP showed a 3.8% annualized growth rate versus an estimate of 3.4% reflecting better spending by consumers than expected.
Albeit early in the quarter, the Atlanta Fed’s GDPNow forecast for Q4 shows an expected 3.7% annualized GDP growth rate (as of 11/2/26). While this estimate tends to be high, it shows initial economic data in the fourth quarter reflecting ongoing growth. Chart 3 shows the ongoing resiliency we have seen in the U.S. economy in recent years with steady economic growth.
Chart 3
Fed Activity
After the first rate increase in over three years in September, the Federal Open Market Committee (FOMC) paused in October with no change in policy rates. Markets widely expected this decision, but there were two dissenting votes as those members voted for another rate hike. The market is currently expecting one additional hike in December and pricing in an additional increase in 2027 (per the CME FedWatch tool as of November 2, 2026). The market is still getting used to Fed Chair Kevin Warsh’s style, which differs from predecessors by not providing much guidance to the market. This change in style could usher in a period of elevated volatility. It is important to note that stocks have historically done well when the Fed is raising rates slowly, which is what the market expectation is at this point.
OUTLOOK
Midterm elections will finally be behind us in short order. The market has been rather calm compared to historical volatility that we tend to experience heading toward midterms. October saw stock market leadership move back toward value stocks compared to growth stock. The difference in relative performance between those two areas of the stock market is noteworthy. Furthermore, the significant headwind of rising rates in the third quarter yielded to a drop in rates in October and a much-needed reprieve in bond weakness as strong returns followed. Stellar earnings from corporate America continue to create a strong fundamental backdrop for the stock market and have been a driving force in the solid equity gains we have seen so far this year. To this point, higher oil prices and elevated interest rates have not derailed economic activity. We need to monitor whether those factors start to slow economic activity, but the economy has been resilient to this point. There is a lot of noise out there, but as always, we believe it is imperative for investors to stay focused on their long-term goals and not let short-term swings in the market, which could materialize at any time, derail them from their longer-term objectives.
Economic Data
| Event | Period | Estimate | Actual | Prior | Revised |
|---|---|---|---|---|---|
| ISM Manufacturing | Sept | 55 | 54.5 | 54.6 | — |
| ISM Services Index | Sept | 55 | 54.9 | 55.4 | — |
| Change in Nonfarm Payrolls | Sept | 90k | 29k | 162k | 133k |
| Unemployment Rate | Sept | 4.10% | 4.20% | 4.10% | — |
| Average Hourly Earnings YoY | Sept | 3.10% | 3.00% | 3.10% | — |
| JOLTS Job Openings | Sept | 7164k | 7523k | 7079k | 7190k |
| PPI Final Demand MoM | Sept | 0.60% | 1.30% | 0.40% | 0.50% |
| PPI Final Demand YoY | Sept | 5.40% | 6.30% | 5.40% | 5.60% |
| PPI Ex Food and Energy MoM | Sept | 0.30% | 0.70% | 0.20% | — |
| PPI Ex Food and Energy YoY | Sept | 4.40% | 5.00% | 4.60% | 4.80% |
| CPI MoM | Sept | 0.60% | 0.60% | 0.40% | — |
| CPI YoY | Sept | 3.60% | 3.70% | 3.40% | — |
| CPI Ex Food and Energy MoM | Sept | 0.20% | 0.30% | 0.30% | — |
| CPI Ex Food and Energy YoY | Sept | 2.50% | 2.60% | 2.40% | — |
| Retail Sales Ex Auto and Gas | Sept | 0.20% | 0.20% | 1.20% | 1.10% |
| Industrial Production MoM | Sept | 0.40% | 0.70% | 0.00% | 0.10% |
| Building Permits | Sept P | 1385k | 1400k | 1403k | __ |
| Housing Starts | Sept | 1305k | 1221k | 1275k | 1288k |
| New Home Sales | Sept | 651k | 676k | 684k | 680k |
| Existing Home Sales | Sept | 3.95m | 3.99m | 3.98m | 3.93m |
| Leading Index | Sept | -0.10% | 0.00% | -0.10% | — |
| Durable Goods Orders | Sept P | 1.90% | 1.80% | -0.10% | 0.10% |
| GDP Annualized QoQ | 3Q A | 3.20% | 3.40% | 2.20% | — |
| U. of Mich. Sentiment | Oct P | 47.6 | 46.3 | 48.1 | — |
| Personal Income | Sept | 0.30% | 0.20% | 0.20% | 0.30% |
| Personal Spending | Sept | 0.60% | 0.50% | 0.90% | — |
| S&P Cotality CS 20-City YoY NSA | Aug | 2.61% | 2.65% | 2.47% | 2.47% |
Source: Bloomberg; P=Preliminary, T=Third ReadingFor illustrative purposes only. Past performance is not indicative of future results. Past actual, projections, or other forward looking statements regarding future financial performance of markets are only projections and actual events or results may differ materially.
Disclosures
Forward looking statements cannot be guaranteed. Past performance is not indicative of future results. The opinions referenced are as of the date of publication and are subject to change due to changes in the market or economic conditions and may not necessarily come to pass. Material presented has been derived from sources considered to be reliable and has not been independently verified by us or our personnel. Nothing herein should be construed as a solicitation, recommendation or an offer to buy, sell or hold any securities, other investments or to adopt any investment strategy or strategies. Investors must make their own decisions based on their specific investment objectives and financial circumstances. Investing involves risk, including loss of principal.
Clark Capital Management Group is an investment adviser registered with the U.S. Securities and Exchange Commission. Registration does not imply a certain level of skill or training. More information about Clark Capital Management Group’s advisory services can be found in its Form ADV and/or Form CRS, which are available upon request.
The manager utilizes a proprietary investment model to assist with the construction of the strategy and to assist the manager with making investment decisions. Investments selected using this process may perform differently than expected as a result of the factors used in the model, the weight placed on each factor, and changes from the factors’ historical trends. There is no guarantee that Clark Capital’s use of a model will result in effective investment decisions.
Fixed income securities are subject to certain risks including, but not limited to: interest rate (changes in interest rates may cause a decline in market value or an investment), credit, prepayment, call (some bonds allow the issuer to call a bond for redemption before it matures), and extension (principal repayments may not occur as quickly as anticipated, causing the expected maturity of a security to increase).
Non-investment-grade debt securities (high-yield/junk bonds) may be subject to greater market fluctuations, risk of default or loss of income and principal than higher-rated securities.
The value of investments, and the income from them, can go down as well as up and you may get back less than the amount invested.
Equity securities are subject to price fluctuation and possible loss of principal. Stock markets tend to move in cycles, with periods of rising prices and periods of falling prices. Certain investment strategies tend to increase the total risk of an investment (relative to the broader market). Strategies that concentrate their investments in limited sectors are more vulnerable to adverse market, economic, regulatory, political, or other developments affecting those sectors.
JOLTS is a monthly report by the Bureau of Labor Statistics (BLS) of the U.S. Department of Labor counting job vacancies and separations, including the number of workers voluntarily quitting employment.
The Core Consumer Price Index (CPI) is a measure of the average change over time in the prices paid by urban consumers for a market basket of consumer goods and services.
The Core Producer Price Index (PPI) program measures the average change over time in the selling prices received by domestic producers for their output. The prices included in the PPI are from the first commercial transaction for many products and some services.
The PCE price index, released each month in the Personal Income and Outlays report, reflects changes in the prices of goods and services purchased by consumers in the United States.
References to market or composite indices, benchmarks or other measures of relative market performance over a specified period of time (each, an “index”) are provided for your information only. Reference to an index does not imply that the portfolio will achieve returns, volatility or other results similar to that index. The composition of the index may not reflect the manner in which a portfolio is constructed in relation to expected or achieved returns, portfolio guidelines, restrictions, sectors, correlations, concentrations, volatility or tracking error targets, all of which are subject to change. Investors cannot invest directly in an index.
The Dow Jones Industrial Average® (The Dow®), is a price-weighted measure of 30 U.S. blue-chip companies.
The index covers all industries except transportation and utilities.
The Bloomberg Barclays U.S. Municipal Index covers the USD-denominated long-term tax exempt bond market. The index has four main sectors: state and local general obligation bonds, revenue bonds, insured bonds and prerefunded bonds.
The Bloomberg US Treasury Index measures US dollar-denominated, fixed-rate, nominal debt issued by the US Treasury. Treasury bills are excluded by the maturity constraint, but are part of a separate Short Treasury Index.
The NASDAQ Composite is a stock market index of the common stocks and similar securities listed on the NASDAQ
stock market.
The S&P 500 measures the performance of the 500 leading companies in leading industries of the U.S. economy, capturing 80% of U.S. equities.
The S&P 500® Equal Weight Index (EWI) is the equal-weight version of the widely-used S&P 500. The index includes the same constituents as the capitalization weighted S&P 500, but each company in the S&P 500 EWI is allocated a fixed weight or 0.2% of the index total at each quarterly rebalance.
The University of Michigan Consumer Sentiment Index rates the relative level of current and future economic conditions. There are two versions of this data released two weeks apart, preliminary and revised. The preliminary data tends to have
a greater impact. The reading is compiled from a survey of around 500 consumers.
The Russell 1000 Index is a stock market index that tracks the highest-ranking 1,000 stocks in the Russell 3000 Index, which represent about 93% of the total market capitalization of that index.
The Russell 2000 Index is a small-cap stock market index that represents the bottom 2,000 stocks in the Russell 3000.
The Russell 3000 Index measures the performance of the 3,000 largest U.S. companies based on total market capitalization, which represents approximately 98% of the investable U.S. equity market.
Russell 1000 Growth Index tracks companies with higher price-to-book ratios, higher sales per share growth, and higher I/B/E/S forecast growth.
Russell 1000 Value Index tracks companies with lower price-to-book ratios and lower expected and historical growth rates. Russell’s value indexes focus more on dividend yield.
Nonfarm payrolls (NFPs) are the measure of the number of workers in the United States excluding farm workers and workers in a handful of other job classifications.
A municipal bond, commonly known as a muni, is a bond issued by state or local governments, or entities they create such as authorities and special districts.
The U.S. Treasury index is based on the recent auctions of U.S. Treasury bills. Occasionally it is based on the U.S. Treasury’s daily yield curve.
The 30 Year Treasury Rate is the yield received for investing in a US government issued treasury security that has a maturity of 30 years.
The Bloomberg Barclays U.S. Corporate High-Yield Index covers the U.S. dollar-denominated, non-investment grade, fixed-rate, taxable corporate bond market. Securities are classified as high-yield if the middle rating of Moody’s, Fitch,
and S&P is Ba1/BB+/BB+ or below.
The Bloomberg Barclays U.S. Credit Index measures the investment grade, U.S. dollar denominated, fixed-rate taxable corporate and government related bond markets.
The Bloomberg Aggregate Bond Index or “the Agg” is a broad-based fixed-income index used by bond traders and the managers of mutual funds and exchange-traded funds (ETFs) as a benchmark to measure their relative performance.
The Bloomberg US Trsy Bellwether 30Y is a U.S. Treasury debt obligation that has a maturity of 30 years.
The ISM Non-Manufacturing Index is an index based on surveys of more than 400 non-manufacturing firms’ purchasing and supply executives, within 60 sectors across the nation, by the Institute of Supply Management (ISM). The ISM Non-Manufacturing Index tracks economic data, like the ISM Non-Manufacturing Business Activity Index. A composite diffusion index is created based on the data from these surveys, that monitors economic conditions of the nation.
ISM Manufacturing Index measures manufacturing activity based on a monthly survey, conducted by Institute for Supply Management (ISM), of purchasing managers at more than 300 manufacturing firms.
The MSCI ACWI ex USA Index captures large and mid cap representation across 22 of 23 Developed Markets (DM) countries (excluding the US) and 27 Emerging Markets (EM) countries*. With 2,359 constituents, the index covers approximately 85% of the global equity opportunity set outside the US.
The Leading Economic Index provides an early indication of significant turning points in the business cycle and where the economy is heading in the near term.
In the United States, the Core Personal Consumption Expenditure Price (CPE) Index provides a measure of the prices paid by people for domestic purchases of goods and services, excluding the prices of food and energy.
The Conference Board’s Leading Indexes are the key elements in an analytic system designed to signal peaks and troughs in the business cycle. The leading, coincident, and lagging economic indexes are essentially composite averages of several individual leading, coincident, or lagging indicators. They are constructed to summarize and reveal common turning point patterns in economic data in a clearer and more convincing manner than any individual component – primarily because they smooth out some of the volatility of individual components.
Gross domestic product (GDP) is the standard measure of the value added created through the production of goods and services in a country during a certain period.
